
Country
Tax in Bolivia Sourced summary, not advice.
 Tax in Bolivia Sourced summary, not advice.
Bolivia (2026): corporate profits tax (IUE) is 25% flat, IVA/VAT is 13%, and the Transactions Tax (IT) is 3% of gross sales. Tax in Bolivia is administered by Servicio de Impuestos Nacionales (SIN). This page gives the headline tax rates on record for Bolivia, the next filing deadline and the main rules.
Bolivia's tax file starts at the Servicio de Impuestos Nacionales
The Servicio de Impuestos Nacionales, the SIN, is the national tax administration. Its public site is impuestos.gob.bo. Customs is a different service. A shipment and a tax return are not the same counter, even when both sit under the finance ministry's broader family. The currency of account is the boliviano. Forms, invoices, and the online office are in Spanish. An English memo for a foreign shareholder is not what the SIN stored.
Bolivia's tax design is built around withholding and around invoicing. A person who pictures a single annual conversation with the administration, of the kind some countries still run for employees only, will miss the monthly machinery. Value added tax, the tax on company profits, and the tax on personal income that is reached through withholding, each have their own account inside the SIN. The names on the SIN menu are the names to use. A translated label on a payroll slide is how a payment lands in the wrong account.
Invoices are the record, not a courtesy
The factura is the document the SIN's system expects for a domestic sale. A receipt that a shop prints for its own files, without the SIN's fields and without the SIN's authorization of the invoice range, does not give the buyer a credit and does not close the seller's sales book. Businesses that arrive from countries where an invoice is a commercial document, and the tax return is a separate annual form, underestimate this. In Bolivia the invoice is the tax record as it happens.
The SIN authorizes invoice ranges. Using a number outside the authorized range, or a layout the office has not accepted, is not a formatting quibble. It is a missing record. Electronic invoicing, where the SIN has rolled it out for a sector, replaces the paper range with a system authorization. The sector list is on impuestos.gob.bo. A vendor's claim that "everyone in this industry is exempt from e-invoicing" is checkable there in an afternoon.
Sponsored. We may earn a commission if you sign up through these links, at no cost to you. How we earn

Buyers who want to deduct VAT need the factura in their own name, with their tax identification number. A factura issued to "cash" or to the wrong number is a commercial piece of paper. It is not a tax credit. Companies that reimburse staff expenses learn this when the credit is refused. The fix is at the till, not in the annual file.
Companies and the tax on profits
Companies registered in Bolivia are in the SIN's company-profit regime. The computation is the statute's, not a copy of a parent company's home-country profit. Depreciation, the treatment of a related-party charge, and the documents that support a deduction are Bolivian questions even when the parent is elsewhere. The SIN can ask for the contract, the invoice, and the proof the service was delivered in or to Bolivia.

A branch of a foreign company and a locally incorporated company are different registrants. The branch does not borrow the parent's foreign tax number. It has its own NIT, the número de identificación tributaria. Payments between the branch and the parent are related-party payments. They need the documents the SIN lists for that kind of charge. Calling the payment a "reimbursement" in an email does not choose the tax character.
Mining, hydrocarbons, and some other sectors carry additional levies that are not the ordinary company-profit tax. Those levies can sit with a different public body even when the SIN still wants the ordinary return. A mining company that files only the SIN profit form and ignores the sector levy has not finished. The sector ministry's page, not a general news article, names the levy.
People, withholding, and work
Employees in Bolivia see income tax largely through withholding by the employer. The employer files the withholding account. The employee does not, in the ordinary case, recompute that tax on a separate annual form the way some other countries require. That does not mean the employee has no records. The payslip and the employer's filing should match. A gap is the employer's problem first, and it becomes the employee's problem if the SIN asks why the withheld amount and the wage book disagree.
Independent people who invoice Bolivian clients issue facturas and fall into the regime the SIN assigns to that activity. Professional services and a shop are not automatically the same regime. The SIN's taxpayer categories are on the site. Choosing the category is a registration step, not a sentence in a proposal.
Social security is not the SIN. The health and pension funds have their own numbers and their own portals. A payroll that shows only a SIN withholding and no social contribution is incomplete for a local employee. The two payments go to different treasuries.
Foreign staff who work in Bolivia are in the Bolivian wage machinery for the days the work is performed here, unless a treaty the country has in force says a shorter stay is exempt and the employer can prove the stay. Bolivia's treaty network is not a global net. Where there is no treaty, domestic withholding is the rule. The foreign employer's certificate of residence does nothing by itself if no treaty gives it an effect.
What to open when a number is in doubt
Open impuestos.gob.bo and match the tax name on the notice to a menu item. Match the NIT. Match the period. A notice that asks for a transfer to a personal account, or that arrives from a domain that is not the SIN's, is not a SIN notice. The office's own portal shows the debt if the debt is real.
This page does not set out rates, brackets, or due days. Those figures move, and the SIN page dated for the period is the figure that counts. It also does not tell a person whether to incorporate, whether to invoice as an individual, or whether a foreign pension is inside a Bolivian computation. A qualified professional in Bolivia, reading the current text on impuestos.gob.bo against the contracts and the facturas, does that work.
Keep the NIT certificate, the invoice authorization, the last three months of purchase and sales books, and the payroll receipts. Those four items answer most of the letters the SIN actually sends. A group chart that shows only the foreign parent does not.
Bolivia and the foreign parent
A foreign group that buys a Bolivian company inherits the target's NIT, its invoice authorizations, and its open SIN periods. The share purchase does not wipe those. Due diligence is a reading of the SIN account, not only of the corporate registry. A clean registry extract with a dirty tax account is a common result.
Related-party charges after the purchase, management fees, royalties, and cost sharing, need the factura or the import document the SIN expects, plus the contract. The currency of the contract can be foreign. The SIN account is still kept in bolivianos. The conversion method is the one the SIN publishes, not the group's monthly average from a spreadsheet in another country.
Staff who move to La Paz or Santa Cruz for the integration are in Bolivian payroll for the work they do there. A home-country certificate of coverage matters only where a social-security agreement exists. The SIN wage withholding and the social fund are still two payments. The relocation letter does not merge them.
Frequently asked
Who is the Bolivian tax authority?
Servicio de Impuestos Nacionales (SIN), under the Ministry of Economy and Public Finance, administers Bolivia's tax system. Customs is handled by Aduana Nacional de Bolivia (ANB). SIN operates a large-taxpayer unit (GRACO) and regional offices. Filings flow through the Oficina Virtual portal. The credentialed profession is Auditor Financiero, regulated by the Colegio de Auditores y Contadores Publicos de Bolivia.
When is the Bolivian annual return due?
RC-IVA personal income tax is withheld monthly by employers -- most employees file no separate annual return. Corporate IUE returns are due 120 days after fiscal year-end (industrial 31 March, mining 30 September, commercial 31 December). IVA is filed monthly on a SIN-staggered calendar. WHT returns are monthly.
Who is a Bolivian tax resident?
Tax residents maintain a permanent place of residence in Bolivia OR are physically present for the majority of the calendar year. Bolivia taxes only Bolivian-source income for both residents and non-residents under a territorial-source framework. Andean Community Decision 578 applies for intra-CAN flows among Bolivia, Colombia, Ecuador, and Peru.
What are the Bolivian personal income tax rates?
RC-IVA applies at 13% flat on employment income above a two-minimum-salary deduction. The distinctive feature: 13% IVA already paid on personal consumption can be credited directly against the 13% RC-IVA liability, often reducing the net PIT rate well below 13%. Self-employment under Regimen General faces IUE at 25%. Investment income WHT is 12.5%.
How does Bolivia's corporate tax work?
IUE 25% on Bolivian-source profit. Hydrocarbons face IDH 32% plus regalias 18% (a 50% floor); mining faces IUE plus a 12.5%/7.5% Alicuota Adicional and a 1-7% Regalia Minera. Financial institutions pay an extra 25% surtax once ROE exceeds 6%. IT at 3% of gross sales runs alongside IUE, creditable against it. Non-resident withholding (IUE-BE) is 12.5%, cut to as low as 3.125% for reinvested profits since March 2026.
What is the Bolivian VAT rate?
Standard IVA 13% under Ley 843 (effective rate ~14.94% on a net-of-IVA base due to Bolivia's gross-price calculation method). Exports are zero-rated. Registration is mandatory regardless of turnover for IVA-scope businesses. ICE excise applies to alcohol, tobacco, fuels, and vehicles. SFE e-invoicing is required for in-scope taxpayers.
From TaxProsRated · our own product
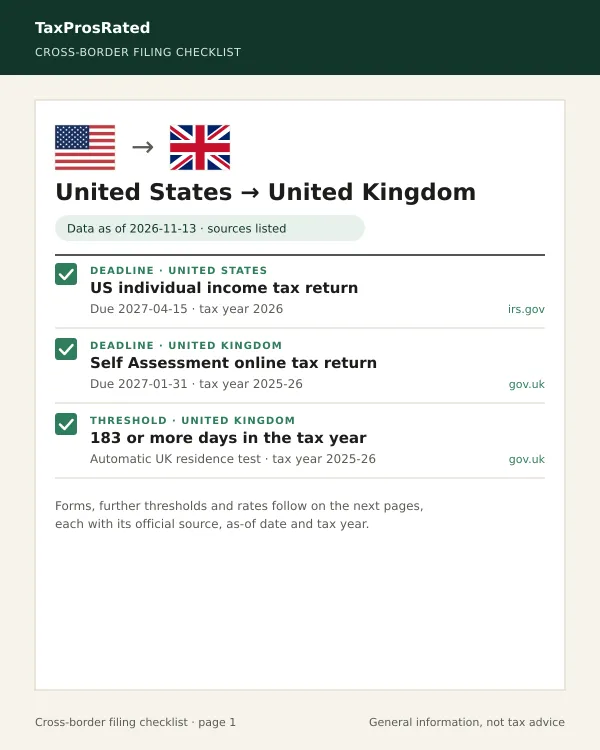
Cross-border filing checklist
- A PDF and a web copy of the checklist for the country pair you choose
- Filing deadlines for both countries, each with the official source URL and as-of date
- The forms named by each tax authority, with a link to the authority's own page
$29 one-time · One payment, no renewal. Tax, if any, is shown at checkout.
More countries in this region · All jurisdictions · Bolivia filing deadlines · Bolivia in the tax rates index · Cross-border filing checklist
Change log
- Country summary updated
- Reviewed against Servicio de Impuestos Nacionales (SIN)
Sources
The figures, dates, and rules on this page are sourced from the documents listed below. Where two sources disagree, both are listed.
Important disclaimer
Informational only — not tax advice. This page summarises publicly available information about tax in Bolivia as of November 2026. Tax laws change, individual circumstances vary, and the application of any rule depends on your specific facts.
TaxProsRated does not provide tax, legal, accounting, or financial advice. Before acting on anything you read here, consult a qualified tax professional licensed in your jurisdiction (in the US: CPA, Enrolled Agent, or attorney; in the UK: CIOT- or ATT-qualified adviser; in Australia: TPB-registered tax agent; elsewhere: a locally-licensed equivalent). TaxProsRated, its operators, and its contributors disclaim all liability for action taken in reliance on this page.