
Country
Tax in Switzerland Sourced summary, not advice.
 Tax in Switzerland Sourced summary, not advice.
ESTV oversees Swiss federal tax; 26 cantonal tax authorities run cantonal and communal income tax. Tax year is the calendar year; cantonal filing deadlines vary, typically 31 March extendable. Federal individual rates run 0–11.5 percent; combined federal-cantonal-communal top rates 22–46 percent by canton. Tax in Switzerland is administered by Swiss Federal Tax Administration (ESTV).
Tax rates
Corporate income tax
FEDERAL direct tax (dBSt) on net profit only; cantonal and communal profit taxes extra and vary; ESTV brochure Das schweizerische Steuersystem, Ausgabe 2025
Top personal income tax
FEDERAL direct tax only; cantonal and communal income taxes extra and vary; 11.5% is the statutory maximum (overall) rate reached at high incomes, per-CHF-100 steps inside the tariff go up to 13.20
VAT / GST (standard)
Federal VAT normal rate; page says currently applicable, no year
Capital gains
Gains on movable private assets (securities, paintings etc.) tax-free at federal and cantonal level; real-estate gains are taxed by cantons; business assets taxable; ESTV brochure Ausgabe 2025
Inheritance / wealth tax
No federal inheritance tax; levied by cantons (spouse and direct descendants generally exempt; rates vary by canton and relationship). A cantonal net-wealth tax also applies
Rate table
CSV| Tax | Rate | As of | Source |
|---|---|---|---|
| Corporate income tax | 8.5Federal direct tax on net profit only | ESTV | |
| Top personal income tax | 11.5Federal direct tax only | ESTV | |
| VAT / GST (standard) | 8.1Federal VAT normal rate | ESTV | |
| Capital gains | not taxedGains on movable private assets tax-free at federal and cantonal… | ESTV | |
| Inheritance / wealth tax | CantonalNo federal inheritance tax | source pending · as of 2026-01-14 |
Who is the tax authority?
Switzerland runs a three-tier tax system with federal, cantonal, and communal layers. At the top, the Eidgenössische Steuerverwaltung (ESTV — Swiss Federal Tax Administration) administers federal direct tax (Direkte Bundessteuer), VAT (Mehrwertsteuer), federal stamp duties, and the 35% federal anticipatory tax (Verrechnungssteuer).
Below the federal level, 26 Kantonale Steuerverwaltungen (cantonal tax authorities) administer cantonal direct tax under the harmonisation framework of the Steuerharmonisierungsgesetz (StHG). Communal tax sits beneath the cantonal layer as a multiplier on cantonal tax.
Tax disputes proceed first through cantonal tribunals, then to the Federal Supreme Court. The dipl. Steuerexperte (EXPERTsuisse) is the principal credentialed tax qualification. The federal portal is estv.admin.ch; each canton operates its own portal.
What is the tax year and when are returns due?
Switzerland's tax year is the calendar year (1 January to 31 December) for both individuals and companies. Most cantons set the individual return deadline at 31 March of the year following the tax year, with extensions widely granted on request — many cantons allow extensions to 30 September or even 30 November.
Corporate returns are due within six months of the fiscal year-end, with extensions commonly available. Mehrwertsteuer (MWST) returns are filed quarterly for most registrants, monthly for net-tax-rate-method registrants, and annually for very small taxpayers.
Who counts as a Swiss tax resident?
Under Article 3 of the Federal Direct Tax Law (DBG/LIFD), an individual is resident in Switzerland if they have their Wohnsitz (domicile) in Switzerland or stay with the intent to remain. The stay triggers residency after 30 days if the person pursues gainful activity, or after 90 days without gainful activity (qualifizierter Aufenthalt).
Sponsored. We may earn a commission if you sign up through these links, at no cost to you. How we earn
Residents are taxed on worldwide income, with foreign permanent establishments and foreign real estate typically excluded via international-allocation rules. Non-residents pay Swiss tax only on Swiss-source income, usually through wage-withholding for cross-border workers (Grenzgänger).
Switzerland's Pauschalbesteuerung (lump-sum taxation) allows certain non-Swiss-citizen new arrivals who do not pursue gainful activity to be taxed on imputed living expenses rather than actual income. The regime is still available in most cantons but has been abolished outright in Zurich, Basel-Stadt, Schaffhausen, Appenzell Ausserrhoden, and Basel-Landschaft.
What are the personal income tax rates?
Swiss personal income tax stacks three layers. Federal Direct Tax (Direkte Bundessteuer) for individuals runs from 0% on the first CHF 14,500 of taxable income, climbing progressively to a maximum federal rate of 11.5% on income above approximately CHF 783,200 (single filers, 2025 scale). Cantonal direct tax follows separate cantonal schedules, broadly harmonised under StHG but with rates that vary dramatically between cantons.
Communal tax operates as a multiplier — typically 50% to 250% of the cantonal rate — depending on the commune. The combined federal-cantonal-communal top marginal rate lands around 22% in low-tax communes (Zug, certain Schwyz communes) and approaches 45–46% in high-tax communes in Geneva, Vaud, and Basel-Stadt.
| Canton | Illustrative combined top rate | Pauschalbesteuerung |
|---|---|---|
| Zug | ~22% | Available |
| Schwyz | ~24% | Available |
| Zurich | ~30% | Abolished |
| Bern | ~42% | Available |
| Vaud | ~45% | Available |
| Geneva | ~45% | Available |
| Basel-Stadt | ~46% | Abolished |
Capital gains on movable private assets (portfolio securities, crypto) are generally exempt at federal level and most cantonal level for non-trader private investors. Vermögenssteuer (wealth tax) is levied at cantonal and communal level on net wealth, with combined rates typically 0.1% to 1.0% per year. The federal 35% Verrechnungssteuer (anticipatory tax) on Swiss-source dividends and bank interest is reclaimed through the cantonal return by Swiss residents.
Deep-dive: see self-employed tax in Switzerland for how federal and cantonal layers combine for sole traders.
How does corporate tax work?
Federal corporate tax (Direkte Bundessteuer) is a flat 8.5% on after-tax profits — effectively 7.83% on the pre-tax profit base. Cantonal corporate tax operates on a separate cantonal base with its own rate schedules; communal corporate tax adds a multiplier on top of the cantonal amount.
Combined effective corporate rates range from about 12% (Zug, Lucerne, Schwyz) to about 21% (Geneva, Bern, Zurich) for 2025. This makes Switzerland one of the more competitive corporate jurisdictions in Europe, particularly at the low-tax end of the canton spectrum.
On after-tax profit — 7.83% on pre-tax basis. Flat rate; no sectoral surcharge unlike most peer jurisdictions.
Federal + cantonal + communal. Zug ~12%; Lucerne ~13%; Zurich ~19.5%; Geneva ~21%.
| Canton | Approx. combined corporate rate |
|---|---|
| Zug | ~12% |
| Lucerne | ~13% |
| Schwyz | ~13.5% |
| Basel-Landschaft | ~17% |
| Zurich | ~19.5% |
| Bern | ~20% |
| Geneva | ~21% |
Switzerland implemented OECD Pillar Two via a constitutional amendment approved in the June 2023 referendum. The Qualified Domestic Minimum Top-up Tax (QDMTT) took effect from 1 January 2024; the Income Inclusion Rule (IIR) applies from 1 January 2025 for groups with consolidated revenue above EUR 750 million. The Beteiligungsabzug (participation deduction) under Articles 69–70 DBG/LIFD reduces corporate tax on qualifying intra-group dividends and capital gains. The Patent Box regime under Article 24a StHG reduces cantonal effective rates on qualifying intellectual-property income.
Deep-dive: see small business tax in Switzerland for sole-trader vs GmbH comparison.
What are the indirect tax rates?
Value Added Tax — Mehrwertsteuer (German) / TVA (French) / IVA (Italian) — is Switzerland's principal indirect tax. The standard rate rose from 7.7% to 8.1% on 1 January 2024, a 0.4-percentage-point increase to fund first-pillar pension (AHV/AVS) financing.
| Rate | Applies to |
|---|---|
| 8.1% | Standard rate — most goods and services |
| 2.6% | Reduced — food, books, newspapers, medicines, select social-policy supplies |
| 3.8% | Accommodation — hotel and lodging supplies |
| 0% | Exports (zero-rated) |
The mandatory MWST registration threshold is CHF 100,000 of worldwide revenue (CHF 250,000 for non-profit and sport associations). Cross-border digital services to Swiss consumers by non-resident vendors above the threshold have been in scope since 2018, with a substantial expansion from 1 January 2025 covering online platforms that facilitate supplies of goods. Switzerland's MWST system is non-EU but broadly mirrors EU VAT principles.
Deep-dive: see VAT in Switzerland for reverse-charge and DDP/DDU import MWST rules.
How are cryptoassets taxed?
The ESTV treats cryptoassets within the standard movable-property framework. For private investors, capital gains on cryptoasset disposals are exempt from federal direct tax and from cantonal direct tax in most cantons — the same treatment as other movable private assets. The exemption depends on private-investor characterisation rather than professional-trader status under ESTV Circular Letter No. 36 (frequency of transactions, holding period, leverage use, and link between trading activity and earned income).
What is the treaty network?
Switzerland maintains approximately 110 comprehensive Double Taxation Conventions (DTAs) in force — one of the largest DTA networks in Europe. This reflects Switzerland's historic position as a financial-services and holding-platform jurisdiction. Most treaties follow the OECD Model with Swiss reservations favouring the exemption method for active income and the credit method for passive income.
Switzerland signed and ratified the OECD Multilateral Instrument (MLI). The MLI's modifications, including the Principal Purpose Test (PPT), apply to many of Switzerland's covered DTAs for periods from 2020 onward. The federal 35% Verrechnungssteuer operates as a structural anti-abuse mechanism — refundable to treaty-eligible non-residents through DTA procedures.
The Beteiligungsabzug (participation deduction) applies to intra-group dividends and capital gains on substantial participations (5% threshold). MLI ratification means the PPT now applies to most covered treaty relationships — treaty-shopping arrangements face anti-avoidance challenge.
Deep-dive: see tax treaty relief in Switzerland for withholding-rate schedules and Verrechnungssteuer refund procedures.
Where does Switzerland sit in the European cohort?
Switzerland anchors the EFTA non-EU cohort alongside Norway, Iceland, and Liechtenstein. It also belongs to the DACH peer group (Germany, Austria, Switzerland) — Germanic civil-law jurisdictions with structurally similar tax frameworks. For comparative positioning, the wider European tax landscape splits into five distinct archetypes:
More on Switzerland
The rest of the Switzerland reference is on the Switzerland tax guide.
Frequently asked
Who is the tax authority in Switzerland?
Three-tier system: ESTV (Swiss Federal Tax Administration) administers federal direct tax, MWST, federal stamp duties, and the federal anticipatory tax. 26 cantonal tax authorities run cantonal direct tax under the harmonised StHG framework. Communal tax operates as a multiplier on cantonal tax. EXPERTsuisse regulates dipl. Steuerexperte and credentialed accountants.
What is the Swiss tax year and the filing deadline?
Tax year is the calendar year. Cantonal deadlines vary, most commonly 31 March of the year following with widely-granted extensions. Federal Direct Tax collected by cantons on behalf of the federation. Companies file within 6 months of fiscal year-end with extensions. MWST returns quarterly for most taxable persons, monthly for net-tax-rate-method, annual for very small.
How is Swiss tax residency determined?
Article 3 DBG/LIFD: Wohnsitz in Switzerland or stay with intent to remain — at least 30 days with employment, 90 days without. Residents taxed on worldwide income (excluding foreign PE and foreign real estate). Lump-sum taxation Pauschalbesteuerung available for non-Swiss-citizen new arrivals not pursuing gainful activity, narrowed federally and abolished by some cantons.
How does Swiss personal income tax work?
Three-layer system. Federal Direct Tax 0–11.5 percent (top above ~CHF 783,200 single). Cantonal direct tax separate, harmonised under StHG with varying rates. Communal multiplier 50–250 percent on cantonal tax. Combined top marginal 22 percent (Zug) to 46 percent (Geneva, Basel-Stadt). Capital gains on private movable assets generally exempt. Wealth tax cantonal-communal at 0.1–1.0 percent.
How does Swiss corporate tax work?
Federal corporate tax 8.5 percent on after-tax profits (7.83 percent on pre-tax). Combined federal-cantonal-communal effective 12 percent (Zug, Lucerne) to 22 percent (Geneva, Zurich). Pillar Two QDMTT effective 1 January 2024; IIR from 1 January 2025 via June 2023 constitutional amendment. Patent Box under Article 24a StHG. Beteiligungsabzug exempts qualifying intra-group dividends.
How does indirect tax work in Switzerland?
MWST/TVA/IVA standard 8.1 percent from 1 January 2024 (raised from 7.7 percent for first-pillar pension financing). Reduced 2.6 percent on food, books, newspapers, medicines. Accommodation rate 3.8 percent on hotels. Mandatory registration CHF 100,000 worldwide revenue (CHF 250,000 non-profits/sport). Cross-border digital and platform-facilitated goods supplies in scope from 2018, expanded 1 January 2025.
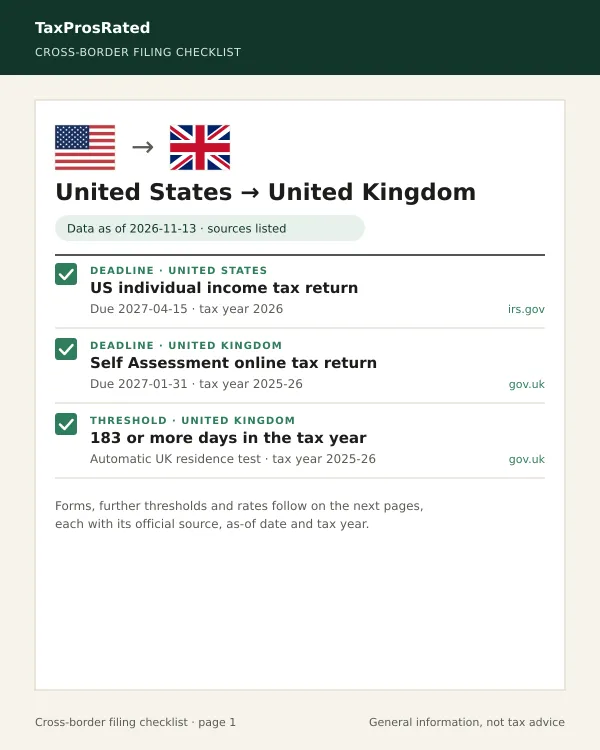
From TaxProsRated · our own product
Cross-border filing checklist
- A PDF and a web copy of the checklist for the country pair you choose
- Filing deadlines for both countries, each with the official source URL and as-of date
- The forms named by each tax authority, with a link to the authority's own page
$29 one-time · One payment, no renewal. Tax, if any, is shown at checkout.
More countries in this region · All jurisdictions · Switzerland filing deadlines · Switzerland in the tax rates index · Cross-border filing checklist
Switzerland tax guides
In-depth guides and explainers relevant to Switzerland.
Change log
- Rate source updated: inheritance
- Rate updated: capital-gains Exempt (movable)->not taxed Source
- Rate updated: corporate-income from 11.9-20.5% to 8.5 Source
- Rate updated: vat from 8.1% to 8.1 Source
- Rate updated: personal-income from 22.2-43.2% to 11.5 Source
- Country summary updated
- Reviewed against Swiss Federal Tax Administration (ESTV)
Sources
The figures, dates, and rules on this page are sourced from the documents listed below. Where two sources disagree, both are listed.
- [3]Source pending
- [4]Source pending
- [5]Source pending
- [6]Source pending
Important disclaimer
Informational only — not tax advice. This page summarises publicly available information about tax in Switzerland as of November 2026. Tax laws change, individual circumstances vary, and the application of any rule depends on your specific facts.
TaxProsRated does not provide tax, legal, accounting, or financial advice. Before acting on anything you read here, consult a qualified tax professional licensed in your jurisdiction (in the US: CPA, Enrolled Agent, or attorney; in the UK: CIOT- or ATT-qualified adviser; in Australia: TPB-registered tax agent; elsewhere: a locally-licensed equivalent). TaxProsRated, its operators, and its contributors disclaim all liability for action taken in reliance on this page.