
Country
Tax in Germany Sourced summary, not advice.
 Tax in Germany Sourced summary, not advice.
The BZSt and Finanzämter administer German tax. Tax year is the calendar year; standard self-filed return is due 31 July, extended to end-February-plus when filed via a Steuerberater. Tax in Germany is administered by Bundeszentralamt für Steuern (BZSt). This page gives the headline tax rates on record for Germany, the next filing deadline and the main rules.
Tax rates
Corporate income tax
KStG § 23 Abs. 1 Nr. 1 (Körperschaftsteuer beträgt für ...); statute steps down to 10% by 2032; solidarity surcharge and municipal trade tax (Gewerbesteuer) not included
Top personal income tax
Marginal rate shown as coefficient 0,45 in the statutory tariff formula (EStG § 32a Abs. 1 Nr. 5, from Veranlagungszeitraum 2026); solidarity surcharge and church tax not included
VAT / GST (standard)
UStG § 12 Abs. 1; statute page states no year
Capital gains
Flat tax on income from capital assets incl. gains on securities (EStG § 32d Abs. 1); solidarity surcharge and church tax extra; other private sales may be taxed as income; statute page states no year
Inheritance / wealth tax
Inheritance/gift tax headline rate; varies by relationship and amount
Rate table
CSV| Tax | Rate | As of | Source |
|---|---|---|---|
| Corporate income tax | 15KStG § 23 Abs. 1 Nr. 1 | gesetze-im-internet.de | |
| Top personal income tax | 45Marginal rate shown as coefficient 0,45 in the statutory tariff… | gesetze-im-internet.de | |
| VAT / GST (standard) | 19UStG § 12 Abs. 1 | gesetze-im-internet.de | |
| Capital gains | 25Flat tax on income from capital assets incl. gains on securities | gesetze-im-internet.de | |
| Inheritance / wealth tax | Up to 50%Inheritance/gift tax headline rate | source pending · as of 2026-01-19 |
DE notes on this page are the question-and-answer record already researched for DE. Read the cited government page before treating a figure as current, and speak with a qualified professional in DE about a filing.
What framework governs capital gains in Germany?
Germany applies two distinct frameworks depending on the asset type. Investment income --- dividends, interest, fund distributions, and gains from selling shares or bonds --- falls under the Abgeltungsteuer (withholding tax) at a flat 25%, established under Section 32d of the Einkommensteuergesetz (EStG).
Private-disposal transactions --- notably real estate and cryptocurrency --- follow a separate holding-period regime under Section 23 EStG, where gains become fully tax-free once a defined period expires. Which framework applies is the threshold question for any German capital-gains analysis.
How does the Abgeltungsteuer work on investment income?
The Abgeltungsteuer (literally: "settlement tax") is a final flat withholding tax of 25% on capital income (Kapitalertrage), as set out in Section 32d EStG. German banks and brokers deduct it automatically at source via the Kapitalertragsteuer (KapESt) mechanism, so most investors with German custody accounts receive net proceeds without needing to file a separate capital-income return.
Sponsored. We may earn a commission if you sign up through these links, at no cost to you. How we earn

On top of the 25% base, a Solidaritatszuschlag (solidarity surcharge) of 5.5% applies to the tax amount itself --- not to the underlying income. This brings the effective combined rate to approximately 26.375% (25% x 1.055). Members of tax-levying religious communities additionally pay Kirchensteuer (church tax) at 8% of the base tax in Bavaria and Baden-Wurttemberg, or 9% in all other federal states, raising the total effective burden to roughly 27.82% or 27.99% respectively. Germany's Federal Constitutional Court upheld the solidarity surcharge in a ruling dated 26 March 2025, leaving approximately six million taxpayers still subject to it.
The Sparer-Pauschbetrag (saver's allowance) under Section 20(9) EStG shields the first EUR 1,000 of annual capital income per individual (EUR 2,000 for married couples assessed jointly) from any withholding. This allowance was increased from EUR 801 / EUR 1,602 effective 1 January 2023. To apply it at source, investors submit a Freistellungsauftrag (exemption order) to each bank; the combined total across all institutions cannot exceed the annual cap.
A Gunstigerprufung (lower-rate check) election under Section 32d(6) EStG is available to taxpayers whose personal marginal income-tax rate falls below 25%. They may elect via Anlage KAP in their annual return to have capital income taxed at the progressive personal rate instead, which can produce a lower overall bill for pensioners or low-income individuals.
| Asset or income type | Holding period | Tax framework | Effective rate (no church tax) |
|---|---|---|---|
| Shares and bonds (any holding) | Any | Abgeltungsteuer | ~26.375% |
| Fund distributions / dividends | Any | Abgeltungsteuer | ~26.375% |
| Equity fund partial-exemption | Any | Abgeltungsteuer (30% exempt) | ~18.46% on eligible gains |
| Real estate (private, investment) | Under 10 years | Section 23 EStG, marginal rate | Up to ~47.5% incl. Soli |
| Real estate (private, investment) | 10 years or more | Fully exempt | 0% |
| Real estate (owner-occupied, qualifying) | Any | Exempt under Section 23(1) Nr. 1 | 0% |
| Cryptocurrency | Under 1 year | Section 23 EStG, marginal rate | Up to ~47.5% incl. Soli |
| Cryptocurrency | 1 year or more | Fully exempt | 0% |
| Other private movable assets | Under 1 year | Section 23 EStG, marginal rate | Up to ~47.5% incl. Soli |
What are the Section 23 EStG private-sale holding-period rules?
Section 23 EStG governs private-disposal transactions (Spekulationsgeschafte) on assets held outside a business. Two holding-period rules determine taxability.
Real estate (Grundstucke): Gains from selling privately held real estate are fully tax-free if the property was held for more than 10 years between acquisition and disposal. Within that 10-year Spekulationsfrist, gains are added to ordinary income and taxed at the taxpayer's progressive marginal rate, which reaches 45% at the top band plus the solidarity surcharge. An important exception applies to owner-occupied residential property: if the property served as the owner's own residence in the year of sale and during the two preceding calendar years, any gain is exempt regardless of how long the property was held --- a provision under Section 23(1) Nr. 1 EStG.
Cryptocurrency and other private assets: Digital assets (including Bitcoin, Ether, and other tokens) are treated as private movable assets under Section 23(1) Nr. 2 EStG. Gains are fully exempt when the holding period exceeds one year. Within one year, gains are taxed at the personal marginal income-tax rate. Note that the Abgeltungsteuer flat rate does not apply to crypto --- the personal rate applies, which can reach 45% plus soli on large gains.
A Freigrenze (exemption threshold) of EUR 1,000 per year applies to total Section 23 EStG private-sale gains: if aggregate gains from all private disposals fall below EUR 1,000 in a calendar year, no tax is owed. This threshold was raised from EUR 600 effective 2024 under the Wachstumschancengesetz (Growth Opportunities Act). Critically, this is a Freigrenze not a Freibetrag: exceeding EUR 999.99 makes the entire gain taxable, not just the amount above the threshold. Section 23 losses from private disposals can only offset other Section 23 gains --- they cannot reduce wages, investment income, or other income categories.
How are investment funds taxed in Germany?
Since the Investment Tax Reform Act of 2018, German investment funds (including ETFs) are subject to a Vorabpauschale --- a notional minimum annual return that investors must recognize as taxable income even without a distribution. The Vorabpauschale equals 70% of the annual base interest rate multiplied by the fund's opening value; for 2025 the base rate was 2.53%. Cumulative Vorabpauschale amounts previously taxed are credited against the final gain on sale to prevent double-counting.
Partial-exemption rates (Teilfreistellung) reduce the taxable base by fund type: equity funds (51%+ equities) receive a 30% exemption, mixed funds (25%+ equities) receive 15%, bond and money-market funds receive none, and real estate funds receive 60% or 80% depending on geographic focus. These exemptions apply to distributions, Vorabpauschale, and disposal gains alike.
For a broader view of how Germany handles cross-border investment income and treaty-reduced withholding rates, see the Germany country overview. Cryptocurrency-specific analysis of staking, mining, and disposal timing is covered in the Germany crypto taxation crossover.
Determining which framework applies to a specific asset, calculating the Vorabpauschale correctly for multi-year fund positions, and claiming Section 23 exemptions via Anlage SO all involve fact-specific analysis. Readers seeking to apply these rules to their own circumstances should consult a qualified Steuerberater (tax consultant) registered with the Steuerberaterkammer.
Capital gains tax in Germany: Abgeltungsteuer 25%, Section 23 EStG private sales, and holding-period rules explained
Germany taxes investment income (dividends, interest, securities gains) under a 25% flat Abgeltungsteuer plus 5.5% solidarity surcharge (effective ~26.375%), with a EUR 1,000 annual Sparer-Pauschbetrag exemption. Private-sale gains follow separate holding-period rules: real estate held over 10 years and crypto held over 1 year are fully tax-free.
What is the Abgeltungsteuer rate including the solidarity surcharge?
The Abgeltungsteuer is 25% on investment income (dividends, interest, securities gains) under Section 32d EStG. The solidarity surcharge adds 5.5% of the tax itself --- not of the income --- producing an effective combined rate of approximately 26.375%. Church-tax members pay an additional 8% or 9% of the base tax, raising the total to roughly 27.82% or 27.99% depending on their federal state.
What is the Sparer-Pauschbetrag and how much is it?
The Sparer-Pauschbetrag is an annual lump-sum exemption on capital income under Section 20(9) EStG. As of 2023 it stands at EUR 1,000 per individual (increased from EUR 801) and EUR 2,000 for married couples filing jointly (increased from EUR 1,602). Investors activate it by submitting a Freistellungsauftrag (exemption order) to their bank; income below the threshold is not subject to Abgeltungsteuer.
How long must I hold German real estate to avoid capital gains tax?
Under Section 23(1) Nr. 1 EStG, privately held real estate is fully exempt from capital gains tax if the holding period exceeds 10 years. Gains realised within 10 years are taxed at the owner's personal marginal income-tax rate, up to 45% plus the solidarity surcharge. An exception applies to owner-occupied residences used by the owner in the year of sale and the two preceding calendar years, which are exempt regardless of holding period.
Is cryptocurrency tax-free in Germany after one year?
Yes. Under Section 23(1) Nr. 2 EStG, cryptocurrency and other private movable assets held for more than one year are fully exempt from income tax on disposal, with no cap on the exempt gain amount. If sold within one year, gains are taxed at the owner's personal marginal rate. Total private-sale gains below EUR 1,000 per year (threshold raised from EUR 600 in 2024) are also exempt regardless of holding period.
How are German equity ETFs and investment funds taxed?
Since the 2018 Investment Tax Reform Act, funds are subject to an annual Vorabpauschale --- a notional minimum return taxed even without a distribution. Partial exemptions reduce the taxable base: equity funds (51%+ equities) receive a 30% exemption, mixed funds (25%+ equities) receive 15%, and bond or money-market funds receive none. The Vorabpauschale previously taxed is credited against the final gain on disposal to prevent double-counting.
Is cryptocurrency tax-free in Germany after one year?
Yes. Section 23(1) No. 2 of the Einkommensteuergesetz (EStG) classifies cryptocurrency as a sonstiges Wirtschaftsgut (other economic good). Private individuals who hold cryptocurrency for more than 12 months and then dispose of it pay no income tax on the gain, regardless of the amount.
The Bundesministerium der Finanzen (BMF) confirmed this treatment in its comprehensive administrative letter of 10 May 2022 -- 'Einzelfragen zur ertragsteuerrechtlichen Behandlung von virtuellen Waehrungen und sonstigen Token' -- and reaffirmed it in the updated letter of 6 March 2025 (titled 'Einzelfragen zur ertragsteuerrechtlichen Behandlung bestimmter Kryptowerte'). The 12-month period runs from the date of acquisition of each specific lot, using the FIFO (first-in, first-out) method where lots cannot be individually identified, per the BMF 2022 and 2025 letters [1].
How are short-term crypto gains taxed?
Disposals within the 12-month holding period generate taxable income reported as sonstige Einkunfte (other income) on Anlage SO of the German income tax return. The gain is added to the individual's total income and taxed at the progressive marginal rate under the EStG. The 2025 brackets for single filers are: 0% up to EUR 12,096; 14% to 42% from EUR 12,096 to EUR 68,429 (geometrically progressive); 42% from EUR 68,430 to EUR 277,825; and 45% above EUR 277,825 [2] (source pending).
A solidarity surcharge (Solidaritaetszuschlag) of 5.5% applies on the income tax amount for higher earners -- with full Soli applying where income tax on total taxable income exceeds approximately EUR 105,500 for single filers [2]. The effective combined top marginal rate (income tax 45% plus Soli 5.5% of that tax) reaches approximately 47.5%. Losses within the holding period offset gains within the same period [1].
What is the EUR 1,000 annual exemption?
Section 23 EStG includes a Freigrenze (threshold) for total private-disposal gains. Importantly, this is a Freigrenze -- not a Freibetrag (allowance). If annual gains from all private disposals (including crypto) stay below EUR 1,000, the entire amount is tax-free. If gains reach or exceed EUR 1,000, the full amount becomes taxable -- there is no partial deduction. The threshold was raised from EUR 600 to EUR 1,000 for tax year 2024 and subsequent years [1]. A separate, lower threshold of EUR 256 applies to income under section 22 No. 3 EStG (covering staking rewards and similar miscellaneous income). The EUR 1,000 and EUR 256 thresholds are independent of each other.
| Situation | Statutory basis | Annual threshold | Tax treatment |
|---|---|---|---|
| Long-term disposal (held >12 months) | ss. 23(1) No. 2 EStG | No limit | Fully tax-free |
| Short-term disposal (held <=12 months), gains below threshold | ss. 23(1) No. 2 EStG | EUR 1,000 (from 2024) | Tax-free |
| Short-term disposal, gains at or above threshold | ss. 23(1) No. 2 EStG | EUR 1,000 (from 2024) | Full gain taxable at marginal rate |
| Staking rewards received | ss. 22 No. 3 EStG | EUR 256 | Tax-free below; full amount taxable above |
| Commercial mining income | ss. 15 EStG | None | Taxable as business income |
How are staking and mining treated?
The 2022 BMF letter (reaffirmed in 2025) resolved a significant area of prior uncertainty regarding staking. Before 2022, some advisers had suggested that lending or staking cryptocurrency could trigger a 10-year holding period extension under section 23(1) No. 2 EStG (the provision that extends the period to 10 years for assets generating income in at least one calendar year). The BMF explicitly rejected this interpretation: staking and lending do not extend the holding period. Cryptocurrency used in staking retains its original 12-month clock, and if the underlying assets were held more than 12 months before disposal, the gain remains tax-free [1]. Staking rewards received are taxable as sonstige Einkunfte under section 22 No. 3 EStG at fair market value in EUR on the date of receipt, with the EUR 256 annual threshold. Mining income follows a different path: mining at commercial scale is classified as business income under section 15 EStG, subject to marginal income tax rates plus Gewerbesteuer (municipal trade tax). Small-scale private mining may qualify as section 22 No. 3 EStG other income with the EUR 256 threshold, but the boundary between hobby and commercial activity depends on scale, equipment, and systematisation [1]. Consult a Steuerberater registered with the Steuerberaterkammer for activity-specific classification. See the Germany country overview for the broader German tax context.
For jurisdiction comparisons, see the Germany country page; the credential-check page links the official registers for checking a German tax professional's registration. All content above summarises publicly available regulatory guidance; it is not a substitute for qualified professional counsel on individual circumstances.
Cryptocurrency Taxation in Germany: The 1-Year Rule, EUR 1,000 Exemption, and Staking
In Germany, cryptocurrency held for more than 12 months by a private individual is fully exempt from income tax on disposal under section 23 EStG. Gains from disposals within 12 months are taxed at the individual's marginal income tax rate (up to 45% plus 5.5% solidarity surcharge), but only if total annual private-disposal gains exceed the EUR 1,000 Freigrenze (threshold) raised from EUR 600 for tax year 2024.
Is crypto tax-free in Germany after one year?
Yes. Under section 23(1) No. 2 EStG, cryptocurrency held for more than 12 months by a private individual is fully tax-free on disposal, with no cap on the exempt gain. The BMF confirmed this in its 2022 and 2025 administrative letters on virtual currencies and crypto-assets. The 12-month period is calculated per acquisition lot using FIFO where lots cannot be individually identified.
How are short-term crypto gains taxed in Germany?
Short-term gains are only taxable if total annual private-disposal gains reach or exceed the EUR 1,000 Freigrenze.
What is the EUR 1,000 crypto exemption in Germany?
Section 23 EStG includes a EUR 1,000 Freigrenze (threshold) for total annual private-disposal gains from 2024. This is a threshold, not an allowance: gains below EUR 1,000 are fully tax-free, but gains at or above EUR 1,000 are entirely taxable with no partial deduction. The threshold was raised from EUR 600 for tax year 2024. A separate EUR 256 threshold applies to staking and mining income under section 22 No. 3 EStG.
Does staking extend the holding period in Germany?
No. The BMF letter of 10 May 2022, reaffirmed in March 2025, explicitly ruled out any extension of the 12-month holding period as a result of staking or lending. Staked cryptocurrency retains its original acquisition date for the 12-month calculation. Staking rewards received are taxable as other income under section 22 No. 3 EStG at fair market value in EUR on receipt, with a EUR 256 annual threshold before the full amount becomes taxable.
How is crypto mining taxed in Germany?
Mining at commercial scale is classified as business income under section 15 EStG, taxable at progressive marginal rates plus Gewerbesteuer; the 12-month holding-period exemption does not apply to business-asset disposals.
Small-scale hobby mining may qualify as other income under section 22 No. 3 EStG with the EUR 256 annual threshold. The boundary between hobby and commercial activity depends on the scale, equipment, and systematisation of the operation; a Steuerberater assessment is required for individual classification.
More on Germany
The rest of the Germany reference is on the Germany tax guide, in 3 parts: part 1, part 2, part 3.
- What is the Abgeltungsteuer and who does it apply to?
- How is the Abgeltungsteuer rate calculated, including the solidarity surcharge?
- What is the Sparer-Pauschbetrag and how does the Freistellungsauftrag work?
- How are equity funds, mixed funds, and bond funds taxed under the Teilfreistellung rules?
- What is the Vorabpauschale and how is it calculated for accumulating funds?
- Dividend and investment income tax in Germany: Abgeltungsteuer 25%, Sparer-Pauschbetrag, Vorabpauschale, and fund Teilfreistellung explained
- What is the exact Abgeltungsteuer rate on dividends and interest in Germany?
- How much is the Sparer-Pauschbetrag and how do I claim it?
- What is the Teilfreistellung partial exemption for equity funds in Germany?
- How is the Vorabpauschale calculated for accumulating ETFs in 2026?
- Can I elect to be taxed at my personal income tax rate instead of the flat 25%?
- What triggers German tax residency?
- What does unlimited tax liability mean in practice?
- German income tax rates and additional levies
- Steuer-ID: the tax identification number
- Exit considerations: Wegzugsteuer and extended limited liability
- Expat tax residency in Germany: Wohnsitz, gewoehnlicher Aufenthalt, and worldwide income obligations
- What is the difference between Wohnsitz and gewoehnlicher Aufenthalt for German tax purposes?
- Does the 183-day rule in a tax treaty override German domestic residency tests?
- What income must a German tax resident report?
- Who still pays the Solidaritaetszuschlag in 2026?
- What triggers the Wegzugsteuer when leaving Germany?
- Who is taxed and at what rate? The three Steuerklassen
- What allowances (Freibetrag) reduce the taxable amount?
- How does the 10-year rolling gift window work?
- What reliefs apply to family homes and business assets?
- Who is subject to German inheritance tax on worldwide assets?
- Inheritance and Gift Tax in Germany 2025: Beneficiary-level Erbschaftsteuer/Schenkungsteuer, three tax classes, EUR 500,000-20,000 Freibetrag, 7-50% rates, 10-year gift window, family-home and business-asset reliefs
- Who pays inheritance tax in Germany -- the estate or the beneficiary?
- What is the personal allowance for a child inheriting from a parent?
- How does the 10-year gift rule affect what a recipient owes on an inheritance?
- Is the family home exempt from inheritance tax in Germany?
- Are worldwide assets taxed if the deceased or heir was a German resident?
- What changed with the Grundsteuer reform effective 1 January 2025?
- How does the Steuermesszahl differ across Lander and property types?
- What is the Hebesatz and how high does it run?
- What is Grunderwerbsteuer and who pays it?
- Who pays Grundsteuer, and can landlords pass it to tenants?
- Property Tax in Germany 2025: Grundsteuer Reform, Lander Models, and Transfer Tax
- Why did Germany reform Grundsteuer in 2025?
- What formula applies to Grundsteuer from 2025?
- How does Bavaria's Grundsteuer model differ from the federal model?
- How much Grunderwerbsteuer does a buyer pay in Germany?
- Can German landlords charge property tax to tenants?
- Are you a Freiberufler or a Gewerbetreibender?
- How does trade tax (Gewerbesteuer) work -- and why does it matter?
- What income-tax rates apply in 2025?
- What is the Kleinunternehmerregelung VAT exemption?
- Social insurance -- mandatory, optional, and the KSK for creatives
- How to register and obtain a Steuernummer
- Self-Employed Tax in Germany 2025: Freiberufler, Gewerbe, Income Tax and VAT
- What professions qualify as Freiberufler in Germany?
- How much Gewerbesteuer does a sole trader pay in Germany?
- What are the 2025 Kleinunternehmerregelung VAT thresholds?
- Are German self-employed required to pay into the state pension?
- When are quarterly income-tax advance payments due in Germany?
- What taxes do German small businesses actually face?
- How are GmbH and UG corporations taxed?
- How are sole traders and partnerships taxed differently?
- What is the Kleinunternehmerregelung VAT exemption?
- How does trade registration (Gewerbeanmeldung) work?
- Small-business tax in Germany 2025: GmbH/UG corporate stack ~30%, Gewerbesteuer, Kleinunternehmer VAT reform, sole-trader credit, Gewerbeanmeldung
- What is the combined corporate tax rate for a GmbH in Germany?
- What are the 2025 Kleinunternehmerregelung thresholds in Germany?
- Do sole traders in Germany get any relief from Gewerbesteuer trade tax?
- What is the difference between a GmbH and a UG in Germany for tax purposes?
- Who must file a Gewerbeanmeldung in Germany and how much does it cost?
- How large is Germany's treaty network, and which authority administers it?
- What is the Freistellungsmethode, and when does it apply?
- When does the Anrechnungsmethode (credit method) apply instead?
- How do non-residents claim treaty-reduced withholding on German dividends and royalties?
- What is the treaty residence tie-breaker, and when does it matter?
- What are the Section 50d EStG treaty-override rules?
- Tax Treaty Relief in Germany: DBA Network, Exemption vs Credit Methods, and the BZSt Refund Procedure
- How many double taxation treaties does Germany have in force?
- What is the Progressionsvorbehalt and how does it affect my German tax bill?
- What withholding rate applies to German dividends paid to non-residents?
- How long does a BZSt withholding-tax refund take, and what is the filing deadline?
- What does Section 50d(3) EStG anti-treaty-shopping mean for holding structures?
- What is German Umsatzsteuer and who must charge it?
- What are the standard and reduced VAT rates?
- How does the Kleinunternehmerregelung small-business exemption work?
- How do advance VAT returns (Voranmeldung) and Vorsteuer deduction work?
- How does the USt-IdNr VAT identification number work, and when is it required?
- German Umsatzsteuer (VAT) Explained: 19% Standard, 7% Reduced, Kleinunternehmer EUR 25k/EUR 100k, OSS, and Vorsteuer
- What is the standard VAT rate in Germany and what does it apply to?
- Which goods and services qualify for the 7% reduced VAT rate?
- What are the 2025 Kleinunternehmerregelung thresholds and what changed?
- How often must VAT advance returns (Voranmeldung) be filed in Germany?
- What is a USt-IdNr and how does a German business obtain one?
Frequently asked
Who is the tax authority in Germany?
The BZSt and the Finanzämter run by the Länder split tax administration. BZSt handles cross-border, the Finanzämter handle day-to-day assessment of income tax, trade tax, and VAT. The BMF issues policy and binding interpretation letters. Steuerberater hold a statutory monopoly on paid tax-advice provision under the Steuerberatungsgesetz.
What is the German tax year and the filing deadline?
The tax year is the calendar year. Self-filed returns are due 31 July of the following year. Filers represented by a Steuerberater receive a statutory extension to end-February of the year-after-following. Voluntary filers (income fully covered by withholding) can file retrospectively for up to four years.
How is German tax residency determined?
Section 1 EStG plus sections 8/9 AO: a person is taxed on worldwide income if they have a Wohnsitz (residence) or a gewöhnlicher Aufenthalt (habitual abode — physically present more than six months without short interruptions). Either trigger creates unlimited liability. AStG section 6 imposes exit tax on emigration of substantial-participation holders.
How does German personal income tax work?
Progressive formula: 0 percent below approximately EUR 11,604 (Grundfreibetrag), linear progressions to 14, 24, then 42 percent up to approximately EUR 68,481, then flat 42 percent, then 45 percent (Reichensteuer) above approximately EUR 277,826. Solidaritätszuschlag of 5.5 percent applies on the top earnings band. Investment income is generally taxed at a flat 25 percent Abgeltungsteuer.
How does German corporate tax work?
Federal Körperschaftsteuer is 15 percent plus 5.5 percent Solidaritätszuschlag = 15.825 percent. Gewerbesteuer adds a federal 3.5 percent multiplied by the municipality's Hebesatz (200–580 percent). Combined effective load typically 28–33 percent. Pillar Two GMT applies for periods on or after 31 December 2023 via the Mindestbesteuerungsgesetz. Zinsschranke caps interest at 30 percent of EBITDA.
How does indirect tax work in Germany?
VAT (Umsatzsteuer): standard 19 percent, reduced 7 percent on basic food, books, public transport, hotel rooms; narrow zero rate on certain photovoltaic installations. Aligns with the EU VAT Directive; OSS and IOSS apply to cross-border B2C. Kleinunternehmerregelung small-business exemption raised to EUR 25,000 prior-year / EUR 100,000 current-year from 1 January 2025.
From TaxProsRated · our own product
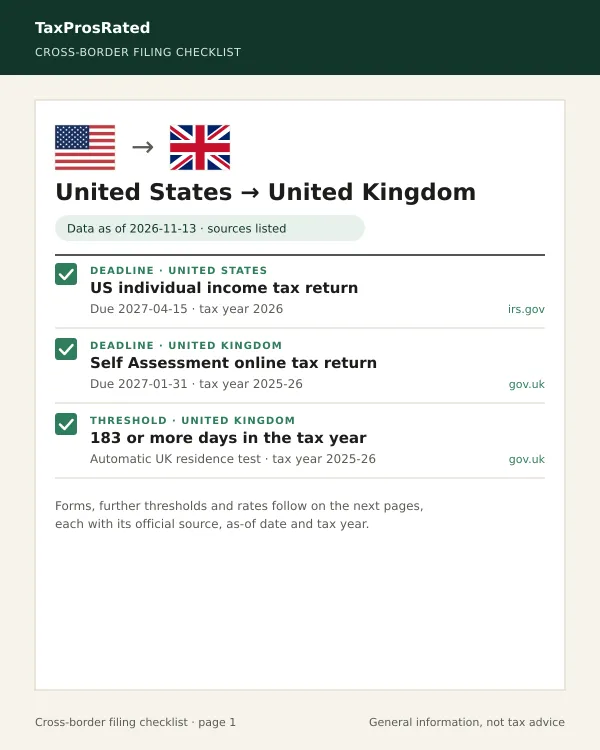
Cross-border filing checklist
- A PDF and a web copy of the checklist for the country pair you choose
- Filing deadlines for both countries, each with the official source URL and as-of date
- The forms named by each tax authority, with a link to the authority's own page
$29 one-time · One payment, no renewal. Tax, if any, is shown at checkout.
More countries in this region · All jurisdictions · Germany filing deadlines · Germany in the tax rates index · Cross-border filing checklist
Germany tax guides
In-depth guides and explainers relevant to Germany.
- GermanyGermany Income Tax Basics: Einkommensteuer ExplainedHow Germany's income tax works: Einkommensteuer, wage-tax withholding, the six Steuerklassen tax classes, and filing your return through ELSTER.
- GermanyGermany Income Tax Return: Einkommensteuererklärung GuideHow residents file a German income tax return: who must file, deadlines, using the ELSTER portal, and the documents you need to get started.
- GermanyGermany's tax return (Steuererklärung): the basicsSome Germans must file a Steuererklärung; many more benefit from doing so voluntarily. ELSTER is the free federal portal for electronic submission.
Change log
- Rate source updated: inheritance
- Rate updated: capital-gains from 26.375% to 25 Source
- Rate updated: corporate-income from ~30% to 15 Source
- Rate updated: vat from 19% to 19 Source
- Rate updated: personal-income from 45% to 45 Source
- Country summary updated
- Reviewed against Bundeszentralamt für Steuern (BZSt)
Sources
The figures, dates, and rules on this page are sourced from the documents listed below. Where two sources disagree, both are listed.
- [11]Source pending
- [12]Source pending
- [13]Source pending
- [14]Source pending
Important disclaimer
Informational only — not tax advice. This page summarises publicly available information about tax in Germany as of November 2026. Tax laws change, individual circumstances vary, and the application of any rule depends on your specific facts.
TaxProsRated does not provide tax, legal, accounting, or financial advice. Before acting on anything you read here, consult a qualified tax professional licensed in your jurisdiction (in the US: CPA, Enrolled Agent, or attorney; in the UK: CIOT- or ATT-qualified adviser; in Australia: TPB-registered tax agent; elsewhere: a locally-licensed equivalent). TaxProsRated, its operators, and its contributors disclaim all liability for action taken in reliance on this page.