
Country
Tax in Dominica Sourced summary, not advice.
 Tax in Dominica Sourced summary, not advice.
Dominica's Inland Revenue Division administers personal income tax at progressive 15/25/35 percent across three bands and corporate income tax at 25 percent flat. VAT is 15 percent. CARICOM, OECS, ECCU, CARIFORUM, and AfCFTA-observer member. Citizenship-by-Investment Programme established 1993 — one of the oldest such programmes in the world. Tax in Dominica is administered by Inland Revenue Division (Dominica).
DM = Dominica (Commonwealth of Dominica) — a small English-speaking island republic of ~70,000 people in the Eastern Caribbean. Independent since 1978. Member of OECS and ECCU. Currency: XCD.
DO = Dominican Republic — a much larger Spanish-speaking republic sharing the island of Hispaniola with Haiti. Population ~11 million. Currency: Dominican Peso (DOP). Entirely separate tax system, language, and legal tradition.
This page covers Dominica (DM) only. For the Dominican Republic, see the DO country page.
Who is the tax authority?
Dominica's Inland Revenue Division (IRD) runs the tax system. IRD sits under the Ministry of Finance, Economic Development and Investment.
Three main statutes frame the system. The Income Tax Act Chapter 67:01 covers personal and corporate income. The VAT Act 2005 governs indirect tax. The Citizenship by Investment Act 2014 governs the CBI programme.
Sponsored. We may earn a commission if you sign up through these links, at no cost to you. How we earn

Dominica belongs to several regional bodies. CARICOM membership unlocks the CARICOM Multilateral Tax Convention. OECS and ECCU membership align the country with the Eastern Caribbean Currency Union. CARIFORUM and AfCFTA-observer status round out the regional posture.
What is the tax year and when are returns due?
Dominica's tax year is the calendar year (1 January to 31 December). PAYE is withheld monthly from employee wages.

Personal returns are due 31 March for the prior year. Corporate annual returns are also due 31 March. Provisional CIT is paid through quarterly installments. VAT-registered businesses file monthly returns.
Who counts as a Dominica tax resident?
An individual is a Dominica tax resident under the Income Tax Act if either rule applies:
- Ordinarily resident in Dominica (permanent home or centre of life)
- Physically present 183 days or more in the tax year
Dominica's income tax operates on a predominantly territorial basis. Residents pay tax on Dominica-source income. The IRD website at ird.gov.dm publishes current residency guidance.
Deep-dive: see expat and cross-border issues in Dominica for the practical rules around moving in or out mid-year.
What are the personal income tax rates?
Dominica uses three income tax brackets with a personal allowance of XCD 30,000:
| Yearly income (XCD) | Tax rate |
|---|---|
| Personal allowance: first 30,000 | 0% |
| 0 to 20,000 (above allowance) | 15% |
| 20,001 to 50,000 | 25% |
| Over 50,000 | 35% |
Social Security contributions also apply:
| Charge | Employee | Employer |
|---|---|---|
| Social Security | 6% | 7.25% |
Deep-dive: see self-employed tax in Dominica for how the charges stack up for freelancers and small businesses.
How does corporate tax work?
Dominica's corporate income tax (CIT) is a flat 25% for resident companies. The rate was reduced from 28.5% post-2024.
Standard CIT rate post-2024 (reduced from 28.5%). Covers most locally-focused businesses — retail, professional services, tourism, agriculture.
Withholding tax on dividends paid to non-residents. Treaty residents may qualify for a reduced rate where the applicable DTA provides one.
The International Business Companies framework was reformed post-2018 with Economic Substance requirements. Tax losses carry forward for 5 years. Dominica has not transposed the OECD Pillar Two global minimum tax.
Deep-dive: see small business tax in Dominica for the sole-trader versus incorporated comparison.
What about VAT and other indirect taxes?
VAT is Dominica's primary indirect tax, introduced under the VAT Act 2005.
| Rate | Applies to |
|---|---|
| 15% | Standard — most goods and services |
| 10% | Hotel accommodation |
| 0% | Exports (zero-rated, not exempt) |
VAT registration is mandatory once annual turnover crosses the threshold published by the IRD. Registered businesses file monthly returns. Dominica also levies environmental levies and specific excise charges on certain goods.
Deep-dive: see VAT and indirect taxes in Dominica for the full VAT mechanics.
How are cryptoassets taxed?
Dominica has no dedicated cryptoasset tax legislation. The Eastern Caribbean Central Bank (ECCB) has issued advisories cautioning about decentralised cryptoassets. Where gains or income are declared, they fall under existing income-tax categories.
Citizenship-by-Investment — one of the world's oldest programmes
Dominica's Citizenship by Investment Programme was established in 1993. It is among the oldest programmes of its kind in the world.
A CBI passport grants Dominican citizenship. It does NOT automatically confer Dominica tax residency. Passport holders who remain non-resident pay Dominica tax only on Dominica-source income. The 183-day physical-presence and ordinary-residence tests apply separately to determine residency.
CBI grantees should consult a qualified practitioner about their home-country tax treatment of the passport acquisition and any residency implications before applying.
Deep-dive: see citizenship and residency in Dominica for the CBI-residency distinction in practice.
What is the treaty network?
Dominica has approximately 5 active bilateral tax treaties. This is a thin network. There is no comprehensive double tax agreement with the United States.
Dominica has signed the OECD Multilateral Instrument (MLI) but not yet ratified it. The CARICOM Multilateral Tax Convention provides regional coverage among Caribbean members. The standard audit statute of limitations is 5 years.
Deep-dive: see tax treaty relief in Dominica for the bilateral rate schedules.
Where does Dominica sit in the Caribbean cohort?
Dominica anchors the Caribbean CBI cohort (Type A) alongside Antigua and Barbuda, St Kitts and Nevis, Saint Lucia, and Grenada. All five operate Citizenship-by-Investment programmes. Dominica is distinct within this cohort — it has a full progressive PIT (unlike Antigua, which abolished PIT), making its tax structure closer to the income-tax cohort while retaining CBI as its best-known feature.
Currency framework — XCD pegged to USD since 1976
The XCD has been pegged to the USD at 2.70 since 1976 under the Eastern Caribbean Currency Union. The ECCB manages monetary policy for all 8 member territories. There is no foreign-exchange risk between XCD and USD for businesses operating in both.
ECCU monetary union — 8-member framework
DM
AG
GD
KN
LC
VC
MS
AI
All 8 ECCU members share the XCD and ECCB monetary policy. DCash, the ECCB's digital currency pilot, operates across the member territories including Dominica. Cross-border commerce within the ECCU uses a single fixed exchange rate — no intra-union currency conversion.
Constitutional context — Commonwealth republic
Dominica became independent in 1978 as a Commonwealth republic — meaning it retained Commonwealth membership while adopting a republican constitution with a President as head of state. This makes it different from constitutional monarchies like Jamaica, Barbados (pre-2021), and Antigua, where the British monarch was head of state.
For tax and legal purposes, Dominica uses English common law (inherited from the British colonial period). Court decisions and legal concepts familiar to practitioners from other common-law jurisdictions generally apply. The IRD operates under the same legal tradition as other ECCU member tax authorities.
More on Dominica
The rest of the Dominica reference is on the Dominica tax guide.
Frequently asked
Who is the Dominica tax authority?
Inland Revenue Division (IRD), under the Ministry of Finance, Economic Development and Investment. IRD operates under the Income Tax Act Chapter 67:01 and VAT Act 2005. The IRD website is ird.gov.dm.
When is the Dominica annual return due?
PAYE withheld monthly. Personal returns due 31 March. Corporate annual returns due 31 March for the prior calendar year. Provisional CIT through quarterly installments. VAT-registered businesses file monthly returns.
Who is a Dominica tax resident?
Tax residents are ordinarily resident in Dominica OR present 183 or more days in the tax year. Dominica taxes residents on Dominica-source income under a predominantly territorial framework. A CBI passport does not automatically confer Dominica tax residency.
What are the Dominica personal income tax rates?
Three brackets with a personal allowance of XCD 30,000: 15% on the first XCD 20,000 above the allowance; 25% on XCD 20,001 to 50,000; 35% on income over XCD 50,000. Social Security: 6% employee and 7.25% employer.
How does Dominica's corporate tax work?
CIT is 25% flat for resident companies (post-2024 reduction from 28.5%). IBC framework reformed post-2018 with Economic Substance requirements. Withholding on non-resident dividends is 15%. Pillar Two has not been transposed. Tax losses carry forward 5 years.
What is the Dominica VAT rate?
VAT is 15% standard rate under the VAT Act 2005. Hotel accommodation uses a reduced 10% rate. Exports are zero-rated.
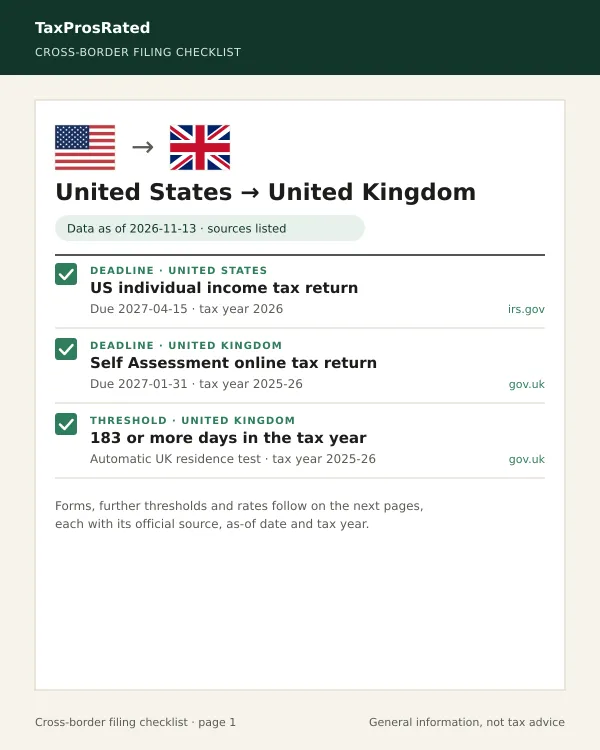
From TaxProsRated · our own product
Cross-border filing checklist
- A PDF and a web copy of the checklist for the country pair you choose
- Filing deadlines for both countries, each with the official source URL and as-of date
- The forms named by each tax authority, with a link to the authority's own page
$29 one-time · One payment, no renewal. Tax, if any, is shown at checkout.
More countries in this region · All jurisdictions · Dominica filing deadlines · Dominica in the tax rates index · Cross-border filing checklist
Change log
- Country summary updated
- Reviewed against Inland Revenue Division (Dominica)
Sources
The figures, dates, and rules on this page are sourced from the documents listed below. Where two sources disagree, both are listed.
Important disclaimer
Informational only — not tax advice. This page summarises publicly available information about tax in Dominica as of November 2026. Tax laws change, individual circumstances vary, and the application of any rule depends on your specific facts.
TaxProsRated does not provide tax, legal, accounting, or financial advice. Before acting on anything you read here, consult a qualified tax professional licensed in your jurisdiction (in the US: CPA, Enrolled Agent, or attorney; in the UK: CIOT- or ATT-qualified adviser; in Australia: TPB-registered tax agent; elsewhere: a locally-licensed equivalent). TaxProsRated, its operators, and its contributors disclaim all liability for action taken in reliance on this page.