
Country
Tax in Saint Kitts and Nevis Sourced summary, not advice.
 Tax in Saint Kitts and Nevis Sourced summary, not advice.
Saint Kitts and Nevis levies NO personal income tax on residents — one of the cleanest zero-PIT regimes globally. Corporate income tax runs at 33% flat. VAT is 17% (10% for hotels). The federation runs the world's oldest Citizenship-by-Investment programme (est. 1984, reformed 2024). Tax in Saint Kitts and Nevis is administered by Inland Revenue Department (St Kitts and Nevis).
Who is the tax authority?
The Inland Revenue Department (IRD), under the Ministry of Finance, administers Saint Kitts and Nevis's tax system. The IRD applies the Income Tax Act Cap 20.22, the VAT Act 2010, and the Companies (Amendment) Act 2018.
The federation has a dual-island structure. Saint Kitts hosts the federal Cabinet and the IRD. Nevis has its own Premier, Nevis Island Assembly, and Nevis Island Administration (NIA) — a separate fiscal authority with its own LLC legislation.
Sponsored. We may earn a commission if you sign up through these links, at no cost to you. How we earn

At the regional level, Saint Kitts and Nevis holds full membership in CARICOM, the OECS, the ECCU, and CARIFORUM. It participates as an AfCFTA observer.
What is the tax year and when are returns due?
The tax year is the calendar year (1 January to 31 December). There are no personal income tax returns because there is no personal income tax.
Who counts as a resident?
Residency is relevant mainly for corporate tax purposes — Saint Kitts and Nevis has no personal income tax on individuals at any rate. Physical presence on either island does not trigger a personal income tax obligation.
For corporate purposes, a company is resident if it is incorporated in the federation or has its central management and control there. Non-resident companies pay withholding tax on dividends sourced from Saint Kitts and Nevis.
The Citizenship-by-Investment (CBI) programme grants citizenship — not tax residency in the sense that would create a new tax obligation. CBI citizens are not taxed on global income by Saint Kitts and Nevis. Their home-country obligations depend entirely on their prior tax residence rules.
Deep-dive: see expat and cross-border tax in Saint Kitts and Nevis for residence-departure rules in practice.
What are the personal income tax rates?
Saint Kitts and Nevis levies no personal income tax on resident individuals. This places it alongside the Bahamas, Cayman Islands, Bermuda, and the UAE as one of the world's cleanest zero-PIT jurisdictions.
Employees and self-employed persons still pay payroll-adjacent charges on wages:
| Charge | Employee | Employer | Self-employed |
|---|---|---|---|
| Social Security | 5% | 5% | 10% |
| Severance Payment Fund | 1% | — | — |
Deep-dive: see self-employed tax in Saint Kitts and Nevis for how charges stack.
How does corporate tax work?
Corporate income tax (CIT) is 33% flat for resident companies. There is no two-tier regulated/unregulated split as in Jamaica — the rate is uniform.
Flat CIT rate. Covers all resident companies. Income Tax Act Cap 20.22 applies. Companies Act 2010 sets the corporate framework.
Withholding on dividends paid to non-residents. Reduced rates apply where a bilateral DTA is in force.
The Companies (Amendment) Act 2018 added an Economic Substance requirement for companies engaged in relevant activities (holding, banking, insurance, shipping, fund management, headquarters, distribution, and service-centre activities). Companies must show adequate people, premises, and expenditure on-island.
Nevis-incorporated entities follow a parallel framework under the Nevis Business Corporation Ordinance and Nevis LLC Ordinance, administered by the Nevis Island Administration (NIA) — discussed further below.
Tax losses carry forward for 5 years, with a 50% cap from year 5 onward. Pillar Two global minimum tax has not yet been transposed.
Deep-dive: see small business tax in Saint Kitts and Nevis for sole-trader versus incorporated comparison.
What about VAT and other indirect taxes?
Value Added Tax (VAT) applies under the VAT Act 2010 at a standard rate of 17%.
| Rate | Applies to |
|---|---|
| 17% | Standard rate — most goods and services |
| 10% | Hotel accommodation and restaurant services |
| 0% | Exports (zero-rated, not exempt) |
VAT registration is mandatory once annual turnover exceeds the threshold set by IRD. VAT-registered businesses file monthly returns.
Other charges include customs duties on imports, an Excise Tax on selected goods (alcohol, tobacco, fuel), a Hotel Accommodation Tax, and a Property Transfer Tax on real-estate transactions.
Deep-dive: see VAT in Saint Kitts and Nevis for the full VAT mechanics.
Meet a Saint Kitts and Nevis resident taxpayer
The world's oldest CBI programme
Citizenship-by-Investment: the original programme
Saint Kitts and Nevis launched the world's first Citizenship-by-Investment programme in 1984 under the Citizenship by Investment Act. Current entry thresholds: USD 250,000 donation to the Sustainable Growth Fund, or USD 400,000+ qualifying real-estate investment. CBI citizenship does not create a new tax-residency obligation in Saint Kitts and Nevis. Due-diligence standards were strengthened by 2024 reforms in response to US Treasury concerns and EU visa-free access requirements.
Nevis LLC — the asset-protection framework
The Nevis LLC Ordinance (1995, refined 2017 and later) creates one of the world's most robust asset-protection LLC regimes. Key features: a one-year statute of limitations on creditor challenges after the transfer date, and a high evidentiary bar for creditors seeking to pierce the LLC veil.
Nevis LLCs are formed through the NIA — not the federal IRD — and follow separate corporate-registry procedures. Companies incorporated on Nevis fall under Nevis law; those incorporated on Saint Kitts fall under federal law. Both islands are part of the same federal tax jurisdiction, but the corporate-law frameworks are distinct.
Currency framework
The XCD has been pegged to the USD at 2.70 since 1976. The Eastern Caribbean Central Bank (ECCB) issues the XCD for all eight OECS member states: KN, AG, DM, GD, LC, VC, MS, and AI.
This common-currency union eliminates intra-OECS exchange-rate risk and simplifies cross-border transactions within the bloc. The ECCB piloted DCash — the world's first central-bank digital currency issued within a currency union — from 2021 to 2024, when the pilot was discontinued.
How are cryptoassets taxed?
Saint Kitts and Nevis does not have a dedicated cryptoasset tax framework. The ECCB has issued advisories cautioning about privately issued cryptoassets, distinct from its own DCash CBDC pilot.
What is the treaty network?
Saint Kitts and Nevis has approximately 6 active bilateral tax treaties. The network is thin compared with larger Caribbean jurisdictions. The CARICOM Multilateral Tax Convention provides regional coverage across member states.
The OECD Multilateral Instrument (MLI) has not yet been ratified. A Switzerland Tax Information Exchange Agreement (TIEA) and a UK FATCA-equivalent arrangement supplement the bilateral treaty network for information-exchange purposes.
Deep-dive: see tax treaty relief in Saint Kitts and Nevis for the bilateral rate schedules.
Where does Saint Kitts and Nevis sit in the OECS cohort?
Saint Kitts and Nevis anchors the OECS Eastern Caribbean cohort alongside seven fellow ECCB members. All eight share the XCD common currency and the OECS treaty framework. Tax regimes vary within the bloc.
More on Saint Kitts and Nevis
The rest of the Saint Kitts and Nevis reference is on the Saint Kitts and Nevis tax guide.
Frequently asked
Who is the Saint Kitts and Nevis tax authority?
The Inland Revenue Department (IRD), under the Ministry of Finance. Nevis also has the Nevis Island Administration (NIA), which handles corporate registration and tax for Nevis-incorporated entities separately from the federal IRD.
When is the Saint Kitts and Nevis annual return due?
There are no personal income tax returns. Corporate annual returns are due 15 April for the prior calendar year. Quarterly estimated corporate tax is due 15 April, 15 July, 15 October, and 15 December. VAT-registered businesses file monthly returns.
Does Saint Kitts and Nevis have personal income tax?
No. Saint Kitts and Nevis levies no personal income tax on residents. Social Security of 5% employee plus 5% employer applies on wages. The Severance Payment Fund adds a 1% employee contribution. There is no tax on investment income, dividends, or capital gains for resident individuals.
How does Saint Kitts and Nevis corporate tax work?
Corporate income tax is 33% flat for resident companies. Non-resident withholding on dividends is 15% (reduced by treaty where applicable). The Companies (Amendment) Act 2018 requires Economic Substance for relevant activities. Tax losses carry forward 5 years with a 50% cap. Pillar Two has not been transposed.
What is the Saint Kitts and Nevis VAT rate?
VAT is 17% standard rate under the VAT Act 2010. Hotel and restaurant services use a reduced 10% rate. Exports are zero-rated. VAT registration is mandatory above the IRD-set annual turnover threshold.
Does the Saint Kitts and Nevis CBI programme affect taxes?
The Citizenship-by-Investment (CBI) programme, established in 1984 as the world's first, grants citizenship — not tax residency in the sense that creates a new tax obligation in Saint Kitts and Nevis. CBI citizens retain their prior home-country tax obligations. The programme was reformed in 2024 with stricter due-diligence requirements.
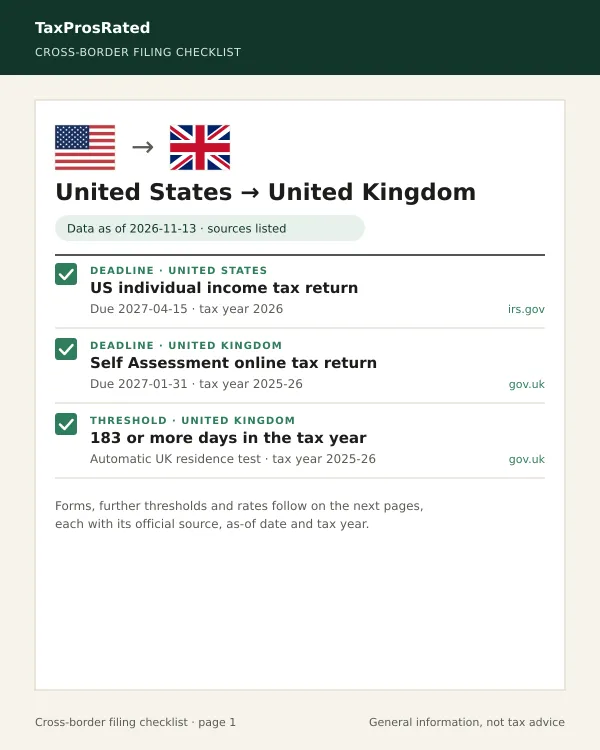
From TaxProsRated · our own product
Cross-border filing checklist
- A PDF and a web copy of the checklist for the country pair you choose
- Filing deadlines for both countries, each with the official source URL and as-of date
- The forms named by each tax authority, with a link to the authority's own page
$29 one-time · One payment, no renewal. Tax, if any, is shown at checkout.
More countries in this region · All jurisdictions · Saint Kitts and Nevis filing deadlines · Saint Kitts and Nevis in the tax rates index · Cross-border filing checklist
Change log
- Country summary updated
- Reviewed against Inland Revenue Department (St Kitts and Nevis)
Sources
The figures, dates, and rules on this page are sourced from the documents listed below. Where two sources disagree, both are listed.
Important disclaimer
Informational only — not tax advice. This page summarises publicly available information about tax in Saint Kitts and Nevis as of November 2026. Tax laws change, individual circumstances vary, and the application of any rule depends on your specific facts.
TaxProsRated does not provide tax, legal, accounting, or financial advice. Before acting on anything you read here, consult a qualified tax professional licensed in your jurisdiction (in the US: CPA, Enrolled Agent, or attorney; in the UK: CIOT- or ATT-qualified adviser; in Australia: TPB-registered tax agent; elsewhere: a locally-licensed equivalent). TaxProsRated, its operators, and its contributors disclaim all liability for action taken in reliance on this page.