
Country
Tax in Kuwait Sourced summary, not advice.
 Tax in Kuwait Sourced summary, not advice.
Kuwait's Department of Income Tax (DIT) runs the system. There is no personal income tax for any resident — citizen or expat. Tax in Kuwait is administered by Ministry of Finance — Tax Department (وزارة المالية). This page gives the headline tax rates on record for Kuwait, the next filing deadline and the main rules.
Kuwait as a hereditary emirate on the Arabian Gulf
The State of Kuwait is a hereditary emirate whose written constitution balances an elected National Assembly, the Majlis al-Umma, against an executive led by the Emir and a prime minister. Arabic is the language of that constitution and of every statute that follows from it. The text treats Islamic sharia as a main source of legislation, which is why a religious levy can sit in the same fiscal conversation as a profits statute without becoming the same charge. Kuwait joined the Cooperation Council for the Arab States of the Gulf and remains inside that council's customs and coordination machinery. It is a United Nations member and a member of the League of Arab States. It is outside the European Union, and the Kuwaiti dinar, issued under the Central Bank of Kuwait, is not a shared currency.
Oil receipts have funded public life for decades, so wage earners often meet the revenue system less often than they would in a state that lives on personal income tax. That history does not freeze the statute book. A new charge would still have to pass through the Emir and the Assembly and then be carried by the Ministry of Finance. Governorates are administrative districts, not separate taxing sovereignties. Failaka, Bubiyan, and the other islands, together with Gulf maritime zones, belong to the same state. A reader arriving from a federation should not expect a stacked provincial return. The real split is institutional: the ministry's tax department, the customs service at ports and land borders, and the Public Institution for Social Security, which collects employment contributions that are not the foreign-company profits tax.
Where Kuwait's gazette and the Ministry of Finance publish rules
Laws and decrees become citable when they appear in the official gazette, Kuwait al-Yawm. Practitioners in Kuwait City treat that gazette as the moment a text is in force. The tax department inside the Ministry of Finance then issues the registrations, circulars, and assessment practice that companies actually follow. The ministry address cited with this essay is the public entrance for that material. TaxProsRated does not store Kuwaiti forms and does not invent branch offices.
The profits tax foreign readers meet is the charge on foreign corporate bodies. For a long time the assessed person has been the foreign company, or the foreign participant in a Kuwaiti enterprise, rather than the employee drawing a salary. Alongside that charge, Kuwaiti shareholding companies can face zakat, a national labour support levy, and a mandatory contribution tied to the Kuwait Foundation for the Advancement of Sciences. Each rests on its own instrument and its own base. Naming them is fair because they are established parts of the published system. Applying them to one company is not fair work for a reference site: share capital, listing, and foreign ownership change the result, and those facts live in the articles and in the ministry's current instructions.
Sponsored. We may earn a commission if you sign up through these links, at no cost to you. How we earn

An English paragraph, including this one, loses to the Arabic gazette if the two diverge. Amendments arrive as laws or as decrees and take effect on the gazette's terms.
Kuwait's borders, Gulf customs practice, and payments abroad
Iraq and Saudi Arabia meet Kuwait by land. Everything else moves through Shuwaikh, Shuaiba, the airport, and the maritime boundary. Inside the Gulf council, a common customs law and a customs-union practice mean that goods already cleared in a partner state are not automatically treated as fresh imports from outside the group. The paperwork that proves that status is a customs file, and this essay will not reconstruct it. Classification, origin, and project-specific relief are decided by the customs administration, not by the tax department that assesses foreign companies.

Kuwait has concluded bilateral treaties covering business profits, dividends, interest, and royalties. The treaty and any protocol, read with whatever substance rule the ministry applies, decide whether a reduced result is available. No ranking of treaty partners appears here, and no holding location is suggested. A payment from Kuwait to a foreign person can still meet withholding under the foreign-corporate rules, and a treaty changes that only when the recipient actually qualifies. Beneficial ownership, a residence certificate, and the local filing the ministry asks for are the usual proof. They are facts, not slogans.
The dinar and the banking system are supervised apart from tax. A large transfer, a salary sent home, or a service fee paid to a foreign parent can raise a central-bank reporting question that has nothing to do with whether profits tax is due. Keeping those questions separate is the only safe reading.
Household life in Kuwait when wages sit outside a general income tax
Citizens and foreign workers who simply earn employment income have lived inside a system whose centre is not a general personal income tax. That is the shape ministries and local practitioners describe. It is not a certificate for one employee. Nationality, a side business, or a commercial registration can pull a person into a different rule, and only the ministry's texts plus someone admitted to practice on Kuwaiti revenue work can apply a real file. Housing support, end-of-service indemnities, and bonuses are labour-law amounts as much as they are fiscal amounts. Reclassifying them is outside this essay.
The Public Institution for Social Security runs a contribution scheme for covered workers, with its own registration and its own wage measure. Kuwaiti nationals and foreign employees are not always covered in the same way. The institution's publications state the difference. Calling those contributions the profits tax would mix two systems.
Rent, Boursa Kuwait shareholdings, and real estate held in a personal name are a third conversation. Kuwait did not build household compliance around an annual personal return of the European or North American kind, yet a company in the ownership chain, or a foreign corporate body, can still bring a charge onto a transaction. Inheritance and family property follow personal-status rules that depend on religion and nationality. Those rules are not a tariff, and they are not restated here.
Someone who remains resident for tax in another country, especially a country that taxes worldwide income, can owe tax at home on Kuwaiti earnings even where Kuwait assesses no personal income tax. Credit, exclusion, and treaty relief in that home system are not questions the Kuwaiti ministry site will answer.
Foreign firms and Kuwaiti companies, and the indirect names that are safe to use
A foreign company active in Kuwait, whether through an agent, a government contract, or a stake in a local entity, is the usual taxpayer for the corporate profits tax. The tax department registers the activity and looks at profits it treats as Kuwaiti. Which expenses pass, how a loss carries, and how an account is accepted are statute and practice. The name of the tax is enough for a country essay.
Shareholding companies of Kuwaiti nationality meet zakat, the labour support levy, and the sciences-foundation contribution instead of, or in a different combination from, the foreign profits tax. Partnerships, sole establishments, and closed companies do not fall in by default. The commercial register is the first document. Petroleum contracts often add fiscal clauses that look like a project bargain rather than the ordinary profits tax. Those clauses stay in the contract and in petroleum legislation.
Indirect taxation needs a narrower claim. Several Gulf neighbours collect a value-added tax under a shared council agreement, and excise on selected goods belongs to that same regional talk. Kuwait has not moved in step with every neighbour. This essay does not say that a value-added tax is being collected in the emirate, and it does not borrow any neighbour's figure. Customs duty under the common customs law is the border charge that can be named with confidence. Any further consumption levy has to be read on the ministry or customs text that is current when the question is asked.
Zones, public tenders, and the choice between a permanent establishment and a deemed-profit assessment can all change the outcome for a contractor. Tender papers and zone rules are primary. A country essay does not close those questions.
What remains undecided after reading about Kuwait
The purpose of these paragraphs is orientation: who legislates, which gazette controls, and which named charges exist. They do not decide that a given company is a foreign corporate body, that zakat is due, that a treaty cuts a withholding, or that a household owes nothing.
They contain no dinar computation and no filing calendar. A live matter belongs on the Ministry of Finance page cited here, and with a qualified professional who practices in Kuwait.
Frequently asked
Who is the Kuwaiti tax authority?
The Department of Income Tax (DIT), under the Ministry of Finance. The DIT administers corporate income tax under Income Tax Decree No. 3 of 1955 (modernized Law No. 2 of 2008) and the Pillar Two DMTT under Decree-Law 157/2024. The Ministry of Finance manages Kuwait's bilateral DTA network.
Does Kuwait have personal income tax?
No. Kuwait has no personal income tax for any resident — Kuwaiti citizens, GCC nationals, and all expatriate workers pay 0% on wages and investment income in Kuwait. No individual return is filed. Expats remain liable to their home-country personal income tax on worldwide income.
When are Kuwaiti tax returns due?
Corporate CIT annual returns are due on the 15th day of the fourth month after fiscal year-end — 15 April for calendar-year companies. Zakat, NLST, and KFAS for listed Kuwaiti companies are coordinated annually. Pillar Two DMTT filings are due under the same DIT mechanism from 2025. No personal income tax filing exists.
How does Kuwait's corporate tax work?
Kuwaiti-owned companies pay 0% CIT. Foreign-owned companies pay 15% flat on taxable profits (Law No. 2 of 2008). Listed Kuwaiti companies owe ~4.5% via Zakat (1%) + NLST (1%) + KFAS (2.5%). Losses carry forward 3 years. Pillar Two QDMTT effective 1 January 2025 for in-scope MNE groups.
Has Kuwait implemented VAT?
No. Kuwait signed the 2017 GCC Unified VAT Agreement but has not enacted VAT legislation as of mid-2026. Kuwait and Qatar are the two remaining GCC holdouts. Customs duty at generally 5% applies on imports under the GCC Unified Customs Union.
What is the Kuwaiti Dinar exchange rate?
1 KWD is approximately 3.25 USD, making the KWD the world's highest-valued currency unit by exchange rate. The KWD is pegged to a basket of currencies (primarily USD-weighted) since 2007, managed by the Central Bank of Kuwait.
From TaxProsRated · our own product
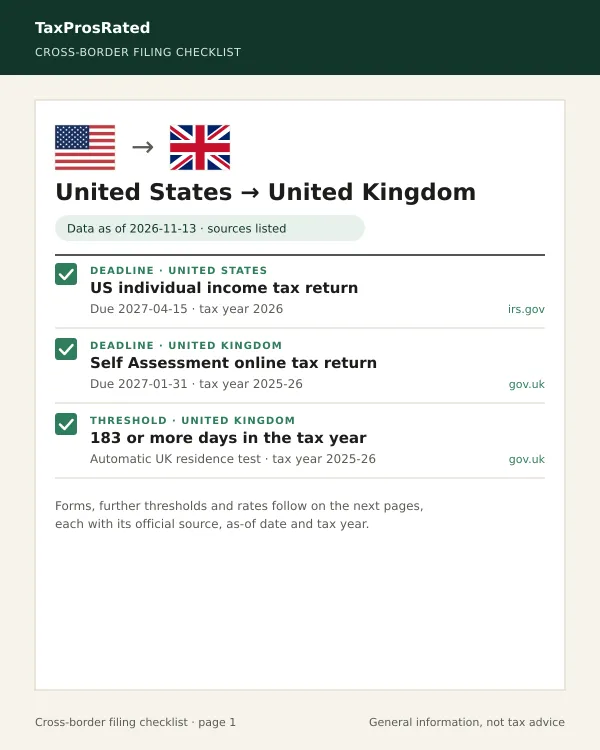
Cross-border filing checklist
- A PDF and a web copy of the checklist for the country pair you choose
- Filing deadlines for both countries, each with the official source URL and as-of date
- The forms named by each tax authority, with a link to the authority's own page
$29 one-time · One payment, no renewal. Tax, if any, is shown at checkout.
More countries in this region · All jurisdictions · Kuwait filing deadlines · Kuwait in the tax rates index · Cross-border filing checklist
Change log
- Country summary updated
- Country summary updated
- Reviewed against Ministry of Finance — Tax Department (وزارة المالية)
Sources
The figures, dates, and rules on this page are sourced from the documents listed below. Where two sources disagree, both are listed.
Important disclaimer
Informational only — not tax advice. This page summarises publicly available information about tax in Kuwait as of November 2026. Tax laws change, individual circumstances vary, and the application of any rule depends on your specific facts.
TaxProsRated does not provide tax, legal, accounting, or financial advice. Before acting on anything you read here, consult a qualified tax professional licensed in your jurisdiction (in the US: CPA, Enrolled Agent, or attorney; in the UK: CIOT- or ATT-qualified adviser; in Australia: TPB-registered tax agent; elsewhere: a locally-licensed equivalent). TaxProsRated, its operators, and its contributors disclaim all liability for action taken in reliance on this page.