
Country
Tax in Liechtenstein Sourced summary, not advice.
 Tax in Liechtenstein Sourced summary, not advice.
Liechtenstein's Steuerverwaltung administers personal income tax at progressive national rates 1–8% plus a municipal multiplier (150–250% of national), giving a combined top effective rate of roughly 22–24%. The wealth tax adds 4% on net assets — distinctive in Europe. Tax in Liechtenstein is administered by Liechtenstein Tax Administration (Steuerverwaltung des Fürstentums Liechtenstein).
Liechtenstein's princely constitution, alpine territory, and Swiss ties
The Principality of Liechtenstein is a constitutional hereditary monarchy on a democratic and parliamentary basis. The reigning prince and the Landtag share the public order described in the constitution, and the government sits in Vaduz. German is the authentic language of legislation. Eleven Gemeinden form the municipal map, and each commune is more than a postal district because the tax statute lets communes set a multiplier on the state assessment. There is no provincial parliament and no second sovereign inside the Rhine valley.
European placement is easy to misread. Liechtenstein is inside the European Economic Area and applies the market rules that membership carries, yet Union membership was never taken up, and the euro was not adopted. The Swiss franc is the currency. A customs treaty folds the principality into the Swiss customs territory, and a currency treaty ties the monetary system to Switzerland. Those treaties are why a parcel cleared under Swiss customs law, and a value-added computation that follows the Swiss Mehrwertsteuer, can be the live rule in Vaduz even though the principality keeps its own direct-tax statute. Neutrality, United Nations membership, and a very small resident population complete the public picture. Financial services, manufacturing along the Rhine, and cross-border work into Switzerland shape who actually meets the Steuerverwaltung.
How Liechtenstein's Landesgesetzblatt and the Steuerverwaltung release texts
The Landesgesetzblatt is the official gazette. A Steuergesetz amendment is citable from that gazette, not from a private reprint. The Steuerverwaltung des Fürstentums Liechtenstein, the tax administration, publishes the practical material: returns, guidance, and assessment notes. Its public site is the address recorded for this jurisdiction. Persons and companies law lives mainly in the Personen- und Gesellschaftsrecht, a code that outsiders sometimes reduce to a slogan about foundations. The code is broader than that. Stiftungen, Anstalten, and ordinary companies are legal forms with civil effects first and fiscal effects second. Tax consequences have to be taken from the tax statute and from the administration's reading, not from the mere fact that a form exists.
Direct taxes on individuals combine an income element and a wealth element, with the communal multiplier applied on top. Legal persons are assessed under an earnings tax, often discussed in German as Ertragssteuer. The administration, not a foreign reference site, decides entity classification, the treatment of a foundation's distributions, and the line between private wealth and a commercial activity. Court review of assessments follows the domestic path through Liechtenstein institutions. English commentary is secondary. If a translation and the Landesgesetzblatt disagree, the gazette is the text that counts.
Liechtenstein cross-border work, Swiss customs, and treaty relief
Because the customs territory is Swiss, goods do not face a separate Liechtenstein tariff wall against Switzerland. Movement toward the European Union is movement out of that Swiss-Liechtenstein customs area, and the formalities are those of the customs union rather than a homemade border code. Travelers who picture an EU internal market without customs posts will misread a trip from Feldkirch or Buchs. The EEA relationship covers a wide set of market rules and still does not turn the principality into an EU member state for the euro, the customs union of the Union, or the Union's own value-added tax directive. Swiss Mehrwertsteuer practice, as extended by treaty, is the consumption-tax system readers should expect to see administered in coordination with Swiss authorities. Confirming the current scope belongs on the official pages, not in a paraphrase.
Sponsored. We may earn a commission if you sign up through these links, at no cost to you. How we earn

Individuals commute across the Rhine in both directions. Employment exercised in Switzerland by a Liechtenstein resident, or the reverse, raises allocation questions under domestic law and under the double-tax treaty with Switzerland. Further treaties with other states divide taxing rights over business earnings and over passive flows such as dividends, interest, or royalty payments. Relief is never automatic: residence, beneficial ownership, and the administration's filing conditions have to be met. Exchange of information and the principality's participation in international transparency standards are real, and they are not the same thing as a tax assessment. A structure that uses a Stiftung or an Anstalt will be looked at for substance. This description stops before any design.
Banking secrecy as a cultural memory is not a current compliance rule. Reporting duties exist. They do not, by themselves, create or erase a Liechtenstein tax debt.
Households assessed by the Liechtenstein tax administration
Resident individuals are brought into the income-and-wealth assessment, and the commune's multiplier changes the amount that finally falls due. Family situation, the distinction between employed income and investment receipts, and the valuation of assets are all handled inside that assessment. No bracket, allowance, or multiplier is printed in these paragraphs. The Steuerverwaltung's own tables are the only place those figures should be read, because they move.
Someone who lives in Vaduz or Schaan and works in the Swiss canton next door must keep two questions apart: where the work is taxed under the treaty, and where the person is resident for the wealth element and for communal attachment. Days of presence, a home, and the centre of vital interests are the kinds of facts the administration weighs. TaxProsRated cannot weigh them. Gift and inheritance consequences, where they arise, follow Liechtenstein civil and fiscal rules and can interact with a foreign heir's home system. The interaction is a case-by-case reading.
Social contributions and compulsory insurance are not the Steuerverwaltung's income-and-wealth tax, even when an employer withholds several lines on one payslip. The line labels matter. New arrivals sometimes assume that EEA free movement imports the tax code of the country they left. It does not. Immigration status, treaty coverage, and tax residence are three different files.
Liechtenstein enterprises, foundations, and the levies with settled names
Companies and other legal persons meet Ertragssteuer on their earnings. The statute defines the base, the participation outcomes, and the treatment of cross-border groups. Those definitions are technical and they change by gazette. Naming the earnings tax is as far as a neutral page should go. Foundations and establishments are not automatically tax-transparent and not automatically taxable like a trading company. The deed, the activity, and the statute decide. Private asset structures and commercial structures are treated differently, and the administration publishes the criteria it uses.
Value-added tax is the Swiss tax as applied in the customs union, not a separately invented Liechtenstein rate card. Registration thresholds, place-of-supply ideas, and invoice duties therefore have to be read in that Swiss-treaty frame, on the official material, with no number copied into this page. Stamp charges or issuance duties, if a transaction meets them, are likewise a matter for the current text rather than for a summary that might be stale.
A permanent establishment of a foreign enterprise, a Liechtenstein company with foreign shareholders, and a foundation holding participations raise three different statute paths. Treaty allocation sits on top of domestic charging rules and does not replace them. Financial-market licensing, where a firm needs it, is a regulatory file at a different office from the Steuerverwaltung. A license is not an assessment.
Appeals and mutual-agreement requests follow their own clocks. An assessment notice from the Steuerverwaltung can be challenged inside the domestic objection path, and a treaty dispute between Liechtenstein and another state can be taken to the competent-authority channel the treaty describes. Neither path is a shortcut around the return. The financial-market regulator licenses certain firms and does not issue the tax assessment. A banking license, an audit opinion, and a tax bill answer three different questions. Residents who also hold Swiss municipal ties, or who sit on the board of a Rhine-valley company, should expect the administration to look at where decisions are actually made.
Where this Liechtenstein page stops
Nothing above decides residence, the communal multiplier that applies to one household, the classification of a Stiftung, or the treaty result on a dividend. No franc amount is calculated. Readers should use the Steuerverwaltung site cited for this principality and speak with someone admitted to handle fiscal work in Liechtenstein.
Frequently asked
Who is the Liechtenstein tax authority?
The Steuerverwaltung (Tax Administration) under the Ministry of Finance. Customs is administered jointly with Switzerland under the 1923 Customs Union Treaty. The Steuerverwaltung portal handles most individual and corporate filings.
When is the Liechtenstein annual return due?
Personal income and wealth tax returns are due 30 April of the year following the tax year. Corporate CIT returns are due 1 July (6 months after year-end). VAT returns are quarterly, filed with the Swiss ESTV — not the Liechtenstein Steuerverwaltung.
Who is a Liechtenstein tax resident?
Tax residents maintain a place of residence in Liechtenstein or are physically present for income-earning purposes over an extended period. Residents pay tax on worldwide income. Non-residents pay tax only on Liechtenstein-source income.
What are the Liechtenstein personal income tax rates?
National PIT is progressive from 1% to 8%. Each municipality adds a multiplier of 150–250% of the national tax. Combined effective top rate is roughly 22–24%. Capital gains at individual non-business level are 0%. The wealth tax adds 4 per mille annually on net assets above the personal allowance.
How does Liechtenstein's corporate tax work?
CIT is 12.5% flat on net taxable profit, with a minimum of CHF 1,800 per year. A notional interest deduction (NID) on equity can reduce the effective rate below 12.5%. Withholding on outbound dividends is 0%. Pillar Two QDMTT applies from 1 January 2024 for MNE groups above €750 million revenue. Tax losses carry forward indefinitely.
What is the Liechtenstein VAT rate?
8.1% standard rate harmonised with Switzerland's MWSTG, raised from 7.7% on 1 January 2024. Reduced rates: 3.8% accommodation, 2.6% basic foodstuffs/books/medicines. Registration threshold CHF 100,000. VAT returns file with the Swiss ESTV, not the Liechtenstein Steuerverwaltung.
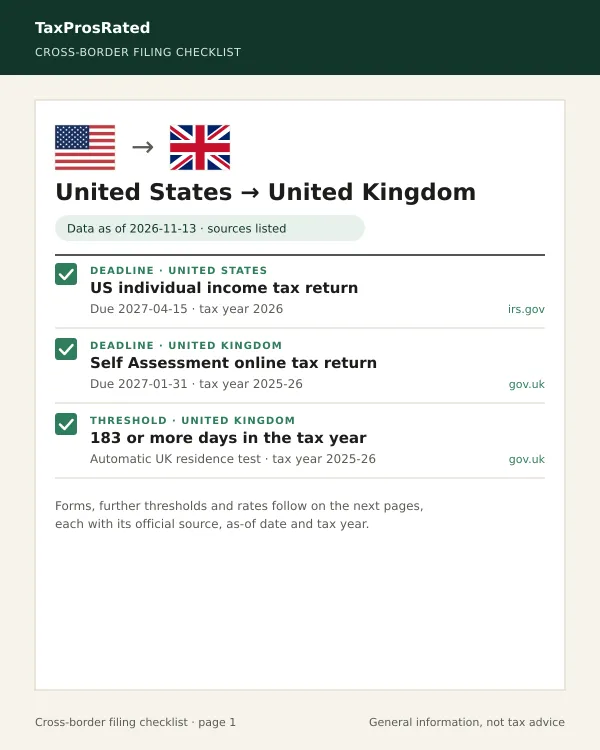
From TaxProsRated · our own product
Cross-border filing checklist
- A PDF and a web copy of the checklist for the country pair you choose
- Filing deadlines for both countries, each with the official source URL and as-of date
- The forms named by each tax authority, with a link to the authority's own page
$29 one-time · One payment, no renewal. Tax, if any, is shown at checkout.
More countries in this region · All jurisdictions · Liechtenstein filing deadlines · Liechtenstein in the tax rates index · Cross-border filing checklist
Change log
- Country summary updated
- Reviewed against Liechtenstein Tax Administration (Steuerverwaltung des Fürstentums Liechtenstein)
Sources
The figures, dates, and rules on this page are sourced from the documents listed below. Where two sources disagree, both are listed.
- [7]Source pending
Important disclaimer
Informational only — not tax advice. This page summarises publicly available information about tax in Liechtenstein as of November 2026. Tax laws change, individual circumstances vary, and the application of any rule depends on your specific facts.
TaxProsRated does not provide tax, legal, accounting, or financial advice. Before acting on anything you read here, consult a qualified tax professional licensed in your jurisdiction (in the US: CPA, Enrolled Agent, or attorney; in the UK: CIOT- or ATT-qualified adviser; in Australia: TPB-registered tax agent; elsewhere: a locally-licensed equivalent). TaxProsRated, its operators, and its contributors disclaim all liability for action taken in reliance on this page.