
Country
Tax in Malaysia Sourced summary, not advice.
 Tax in Malaysia Sourced summary, not advice.
LHDN (Inland Revenue Board of Malaysia) administers Malaysian direct tax under the Income Tax Act 1967. The Year of Assessment is the calendar year; Form BE is due 30 April and Form B (business income) by 30 June. Tax in Malaysia is administered by Inland Revenue Board (LHDN).
Tax rates
Corporate income tax
Standard company rate; SMEs 15%/17% on first tranches; latest years shown on page are YA 2023-2024
Top personal income tax
Resident individuals; chargeable income exceeding RM2,000,000; latest years shown on page
Lowest personal income tax
Lowest non-zero band; first RM5,000 at 0%; resident individuals
Rate table
CSV| Tax | Rate | As of | Source |
|---|---|---|---|
| Corporate income tax | 24Standard company rate | LHDN | |
| Top personal income tax | 30Resident individuals | LHDN | |
| Lowest personal income tax | 1Lowest non-zero band | LHDN |
Who is the tax authority in Malaysia?
The Inland Revenue Board of Malaysia (LHDN — Lembaga Hasil Dalam Negeri Malaysia) is the principal direct-tax authority. LHDN was established under the Inland Revenue Board of Malaysia Act 1995 and operates under the Ministry of Finance.
LHDN administers four main statutes: the Income Tax Act 1967, the Petroleum (Income Tax) Act 1967, the Real Property Gains Tax Act 1976, and the Stamp Act 1949. The Royal Malaysian Customs Department (Jabatan Kastam DiRaja Malaysia) administers Sales Tax under the Sales Tax Act 2018 and Service Tax under the Service Tax Act 2018.
Sponsored. We may earn a commission if you sign up through these links, at no cost to you. How we earn

Disputes are reviewed by the Special Commissioners of Income Tax and the Tax Appeal Tribunal. The Malaysian Institute of Accountants (MIA) regulates credentialed accountants; the Chartered Tax Institute of Malaysia (CTIM) administers the Chartered Tax Practitioner credential.
What is the Malaysian tax year and when are returns due?
The Malaysian Year of Assessment for individuals is the calendar year (1 January to 31 December). Form BE — for resident individuals without business income — is due 30 April. Form B — for resident individuals with business income — is due 30 June. Form M covers non-resident individuals.

Online filing carries a standard 15-day extension. Tax agents receive longer extensions through the agent-extension framework administered by LHDN. Companies file Form C within seven months of their fiscal year-end.
Salaried employees participate in the Monthly Tax Deduction framework (Potongan Cukai Bulanan — PCB), where the employer withholds estimated tax each month. Self-employed and business filers make Estimated Tax (Anggaran Cukai) instalments under section 107C ITA. SST returns are filed bi-monthly, with payment due by the last day of the following month.
How is Malaysian tax residency determined?
Section 7 of the Income Tax Act 1967 sets four separate residency tests. Any single test triggers full-year residency for that Year of Assessment.
What are the personal income tax rates?
Resident individuals are taxed on a ten-bracket progressive scale. The brackets for YA 2025 are:
| Chargeable income (MYR) | Rate |
|---|---|
| First 5,000 | 0% |
| 5,001 to 20,000 | 1% |
| 20,001 to 35,000 | 3% |
| 35,001 to 50,000 | 6% |
| 50,001 to 70,000 | 11% |
| 70,001 to 100,000 | 19% |
| 100,001 to 400,000 | 25% |
| 400,001 to 600,000 | 26% |
| 600,001 to 2,000,000 | 28% |
| Above 2,000,000 | 30% |
The personal allowance is MYR 9,000 for the filer plus additional relief for a dependent spouse, dependent children, parents' medical expenses, lifestyle expenses, EPF (Employees Provident Fund) contributions, life insurance, and Private Retirement Scheme contributions. Non-residents are taxed at a flat 30 percent on Malaysian-source employment income.
How does Malaysian corporate tax work?
The standard corporate income tax (CIT) rate for resident companies is 24 percent on chargeable income above MYR 600,000. Small-and-medium enterprises (paid-up capital of MYR 2.5 million or below, gross income from business sources of MYR 50 million or below) are taxed at graduated rates: 15 percent on the first MYR 150,000, 17 percent on the next MYR 450,000, and 24 percent above MYR 600,000.
Resident companies on chargeable income. Petroleum companies taxed separately under PITA 1967.
Paid-up capital ≤MYR 2.5M and gross business income ≤MYR 50M per year.
Groups with consolidated revenue above EUR 750 million from 1 January 2025. Income Inclusion Rule + Domestic Top-up Tax via Finance (No. 2) Act 2023.
10% CIT or a flat RM 20,000 on qualifying Labuan trading income for entities in the Labuan IBFC special economic zone.
Petroleum companies operate under the Petroleum (Income Tax) Act 1967 with sector-specific rates. The Controlled Foreign Company (CFC) regime was introduced by Finance Act 2023 and applies from YA 2025. Investment incentives include Pioneer Status, Investment Tax Allowance, MIDA-administered grants, and the Special Reinvestment Allowance.
How does indirect tax work in Malaysia?
Malaysia replaced the Goods and Services Tax (in force 2015–2018) with the dual Sales Tax and Service Tax (SST) regime from 1 September 2018. The two taxes operate independently — a business may be registered for one but not the other.
| Tax | Standard Rate | Key Threshold |
|---|---|---|
| Sales Tax (manufactured goods) | 5% or 10% | MYR 500,000 annual taxable revenue for manufacturers |
| Service Tax | 8% (raised 1 Mar 2024) | MYR 500,000 to MYR 1.5M depending on category |
| F&B and selected telecoms (Service Tax) | 6% (some categories retained) | — |
| Sales Tax on Low-Value Goods (imports) | As above | Threshold on imported consumer goods post-2022 reform |
Excise duties apply on alcohol, tobacco, fuel, motor vehicles, sugary drinks, and selected other categories. Customs duties cover imports and are administered by the Royal Malaysian Customs Department.
How are cryptoassets taxed in Malaysia?
LHDN issued the Guidelines on Tax Treatment of Digital Currency Transactions in 2022. The guidelines apply a badges-of-trade analysis to distinguish active traders from capital investors.
What is the new capital gains tax on unlisted shares?
From YA 2024, gains on the disposal of unlisted shares of Malaysian and foreign-incorporated companies are subject to Capital Gains Tax under the new section 4(aa) of the Income Tax Act 1967. The rate is 10 percent.
What is the Malaysian treaty network?
Malaysia maintains approximately 80 comprehensive Double Taxation Avoidance Agreements — one of the largest DTA networks in ASEAN. Most treaties follow the OECD Model Convention with Malaysian-specific reservations on the credit-versus-exemption method (Malaysia generally applies the credit method) and on source taxation of technical services.
Malaysia signed and ratified the OECD Multilateral Instrument. The MLI's modifications, including the Principal Purpose Test (PPT), apply to many of Malaysia's covered DTAs for periods from 2022 onward. Transfer-pricing rules under section 140A ITA mirror OECD principles, with safe-harbours and an Advance Pricing Arrangement programme administered by LHDN's Multinational Tax Department.
Where does Malaysia sit in the ASEAN-Pacific cohort?
Malaysia anchors the SST-regime cohort in the ASEAN-Pacific tax landscape. Five cohort types describe the region:
Common pitfalls and things to watch
Several recurring issues affect individuals and businesses operating in Malaysia:
The exemption for individual foreign-source income runs only through 31 December 2026 under its current extension. It carries specific carve-outs for certain partnership and investment income. Each renewal is legislated separately.
Most service categories moved from 6 percent to 8 percent under the Budget 2024 measures. Food-and-beverage and certain telecoms categories were retained at 6 percent. Businesses that did not update their invoicing systems on 1 March 2024 may have under-collected.
Section 4(aa) ITA CGT at 10 percent applies to disposals of unlisted Malaysian and foreign-incorporated shares from 1 January 2024. This is separate from RPGT. The choice of gross-price versus net-gain method must be made carefully before disposal.
The Controlled Foreign Company regime introduced by Finance Act 2023 applies for Years of Assessment from 2025 onward. Malaysian-resident controlling shareholders of low-tax foreign entities must assess whether attribution rules apply to their holding structure.
Groups with consolidated revenue above EUR 750 million are subject to the GloBE Income Inclusion Rule and the Domestic Top-up Tax implemented through Finance (No. 2) Act 2023. Malaysia is an early ASEAN adopter of Pillar Two.
The 182-day count is just one of four tests under section 7 ITA. The linking-period test and the 90-day-with-prior-years test can trigger full-year residency even when the 182-day count is not met — a common source of unexpected liability for short-stay professionals.
Entities in the Labuan International Business and Financial Centre operate under a separate 10 percent CIT or flat RM 20,000 regime for qualifying international trading income. The substance requirements under post-2019 reforms are strict; failing them collapses the entity into the standard 24 percent rate.
When is a Malaysian tax professional worth consulting?
Some situations can be managed through LHDN's MyTax portal and standard PCB tables. Others involve genuine complexity:
Specific circumstances where practitioner input is commonly sought include: holding unlisted shares being disposed of under the section 4(aa) CGT regime; operating a business in a petroleum-related sector under the PITA; relocating to or from Malaysia mid-year and navigating the four residency tests; managing a corporate group subject to Pillar Two or the new CFC rules; establishing operations in the Labuan IBFC or under Pioneer Status; receiving a LHDN notice of assessment, audit selection letter, or instalment-revision request; and dealing with any cross-border structure covered by a DTA or the MLI's PPT provisions.
This page is general information. It is not personal guidance for any specific situation. Tax rules change. Always check current figures on the LHDN website or with a credentialed CTIM practitioner before filing.
Frequently asked
Who is the tax authority in Malaysia?
LHDN (Lembaga Hasil Dalam Negeri Malaysia / Inland Revenue Board of Malaysia) under the Ministry of Finance administers Income Tax Act 1967, Petroleum (Income Tax) Act 1967, RPGT Act 1976, and Stamp Act 1949. Royal Malaysian Customs Department administers Sales Tax Act 2018 and Service Tax Act 2018 plus customs and excise. Special Commissioners of Income Tax handle dispute review. MIA and CTIM regulate the principal credentialed professions.
What is the Malaysian tax year and filing deadline?
Year of Assessment is the calendar year. Form BE (individuals without business income) is due 30 April; Form B (business income) is due 30 June; Form M covers non-residents. A standard 15-day online-filing extension applies; tax agents receive longer extensions. Salaried employees use PCB (Potongan Cukai Bulanan) monthly employer withholding. Companies file Form C within seven months of fiscal year-end. SST returns are filed bi-monthly.
How is Malaysian tax residency determined?
Section 7 ITA 1967 sets four tests — any one triggers full-year residency: 182 days physically present in the Year of Assessment; the linking-period test where fewer than 182 days in the YA but linked to a 182-plus-day basis period across adjacent years; 90 days in the YA plus residency in 3 of 4 preceding YAs or the following YA; or residency in all 3 preceding YAs plus the following YA. Foreign-source income for individuals is currently exempt through 31 December 2026 with carve-outs.
What are the Malaysian personal income tax rates?
Resident progressive: 0/1/3/6/11/19/25/26/28/30 percent across MYR 5k/20k/35k/50k/70k/100k/400k/600k/2M/above. Personal allowance MYR 9,000 plus dependent reliefs. Lifestyle, parents' medical, EPF, life insurance, and PRS deductions available. No comprehensive CGT for non-real-property assets except the new section 4(aa) CGT at 10 percent on unlisted-share disposals from YA 2024. Non-residents are taxed at a flat 30 percent on Malaysian-source employment income.
What is the new Capital Gains Tax on unlisted shares?
From YA 2024, section 4(aa) of the Income Tax Act 1967 imposes CGT at 10 percent on gains from disposing of unlisted Malaysian and foreign-incorporated company shares. Two calculation methods apply: 10 percent on gross disposal price, or — by election — 10 percent on chargeable gain net of allowable cost. This is separate from the RPGT Act 1976, which continues to apply only to real property and real-property-company shares.
How does Malaysian corporate tax work?
Resident corporate rate is 24 percent. SMEs (paid-up capital under MYR 2.5M and gross business income under MYR 50M) pay 15 percent on first MYR 150k, 17 percent on next MYR 450k, then 24 percent. Pillar Two GloBE applies from 1 January 2025 for groups with consolidated revenue above EUR 750 million. CFC rules apply from YA 2025. Labuan IBFC qualifying trading income taxed at 10 percent or flat RM 20,000. Pioneer Status and ITA investment incentives available.
From TaxProsRated · our own product
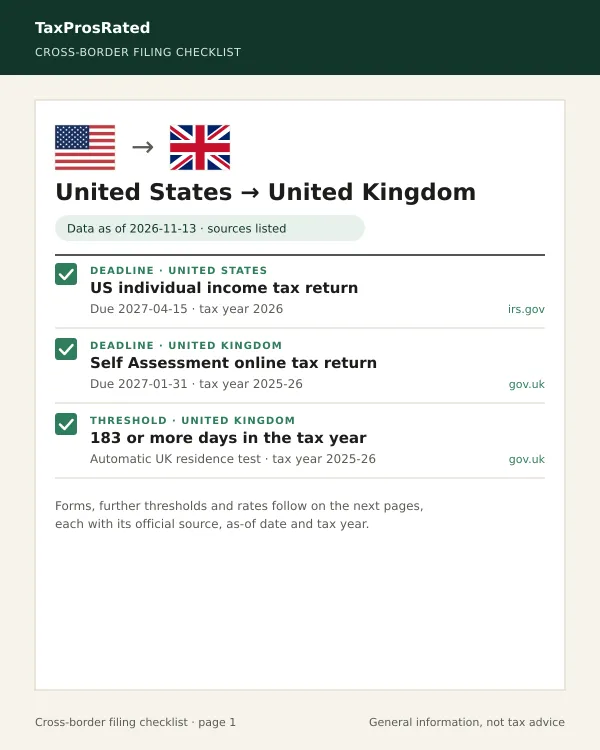
Cross-border filing checklist
- A PDF and a web copy of the checklist for the country pair you choose
- Filing deadlines for both countries, each with the official source URL and as-of date
- The forms named by each tax authority, with a link to the authority's own page
$29 one-time · One payment, no renewal. Tax, if any, is shown at checkout.
More countries in this region · All jurisdictions · Malaysia filing deadlines · Malaysia in the tax rates index · Cross-border filing checklist
Malaysia tax guides
In-depth guides and explainers relevant to Malaysia.
- MalaysiaMalaysia Personal Income Tax: The BasicsHow personal income tax works in Malaysia: LHDN, the 182-day residency rule, Forms BE/B/M, deadlines, and how to file and pay.
- MalaysiaMalaysia Income Tax Basics: Filing, Rates, and DeadlinesHow income tax works in Malaysia: who files, the 182-day residency test, progressive rates, and filing on time through LHDN's MyTax portal.
Change log
Sources
The figures, dates, and rules on this page are sourced from the documents listed below. Where two sources disagree, both are listed.
- [3]Source pending
- [4]Source pending
- [5]Source pending
- [6]Source pending
Important disclaimer
Informational only — not tax advice. This page summarises publicly available information about tax in Malaysia as of November 2026. Tax laws change, individual circumstances vary, and the application of any rule depends on your specific facts.
TaxProsRated does not provide tax, legal, accounting, or financial advice. Before acting on anything you read here, consult a qualified tax professional licensed in your jurisdiction (in the US: CPA, Enrolled Agent, or attorney; in the UK: CIOT- or ATT-qualified adviser; in Australia: TPB-registered tax agent; elsewhere: a locally-licensed equivalent). TaxProsRated, its operators, and its contributors disclaim all liability for action taken in reliance on this page.