
Country
Tax in United States Sourced summary, not advice.
 Tax in United States Sourced summary, not advice.
The IRS runs US federal tax. The tax year is the calendar year. The personal filing deadline is 15 April with a six-month extension available. Citizens and resident aliens pay tax on worldwide income at graduated rates from 10% to 37%. Corporations pay a flat 21% federal rate. Tax in United States is administered by Internal Revenue Service (IRS).
Tax rates
Corporate income tax
Federal only; state corporate taxes extra; Publication 542 revision 01/2024, no later revision on page
Top personal income tax
Federal only; state and local income taxes extra; single-filer table row
Lowest personal income tax
Federal only; state and local income taxes extra; single-filer table row
Capital gains
Federal maximum rate on most long-term net capital gain (0%/15%/20% by income); short-term gains taxed as ordinary income; other exceptions on page; state taxes extra
Rate table
CSV| Tax | Rate | As of | Source |
|---|---|---|---|
| Corporate income tax | 21Federal only | IRS | |
| Top personal income tax | 37Federal only | IRS | |
| Lowest personal income tax | 10Federal only | IRS | |
| Capital gains | 20Federal maximum rate on most long-term net capital gain | IRS |
US notes on this page are the question-and-answer record already researched for US. Read the cited government page before treating a figure as current, and speak with a qualified professional in US about a filing.
Understanding how the United States taxes capital gains requires separating two fundamentally different rate systems: the preferential long-term rates that apply to assets held more than one year, and the ordinary income rates that apply to assets held one year or less. The distinction can reduce the federal tax on a given gain by as much as 17 to 20 percentage points, which is why the holding period is one of the most consequential variables in any capital-asset disposition.
What rate applies to short-term capital gains?
A net short-term capital gain -- from an asset held one year or less -- is taxed as ordinary income at the filer's applicable marginal rate, which ranges from 10 to 37 percent under the seven federal income tax brackets in effect for 2025 (Rev.
Proc. 2024-40). [1] Because short-term gains stack on top of wages and other ordinary income, a high-bracket filer can pay the 37 percent top rate on a short-term gain that would attract only 15 or 20 percent if the holding period exceeded one year. The IRS defines "one year or less" strictly: an asset sold exactly 365 days after purchase is short-term; a sale on day 366 or later is long-term under IRC Section 1222.
What are the 2025 long-term capital gains rate brackets?
For tax year 2025 (returns filed in 2026), IRS Rev. Proc. 2024-40 sets the long-term capital gains brackets as follows, applied to taxable income by filing status. [1] The table below summarizes the three rates and income thresholds:
What is the Net Investment Income Tax and when does it apply?
The Net Investment Income Tax (NIIT) under IRC Section 1411 is an additional 3.8 percent tax assessed on the lesser of net investment income or the amount by which modified adjusted gross income (MAGI) exceeds applicable thresholds: $200,000 for single filers and heads of household, $250,000 for married filing jointly and qualifying surviving spouses, and $125,000 for married filing separately. [2] These thresholds are not adjusted for inflation and have remained fixed since the NIIT took effect in 2013.
Sponsored. We may earn a commission if you sign up through these links, at no cost to you. How we earn
Net investment income subject to the NIIT includes interest, dividends, capital gains, rental and royalty income, and non-qualified annuities. [2] Capital gains excluded from income under Section 121 (the principal-residence exclusion) are also excluded from NIIT. Wages, unemployment compensation, Social Security benefits, and distributions from qualified retirement accounts are not net investment income and are therefore excluded from the NIIT base. Filers who owe NIIT must file Form 8960.
How does the Section 121 primary-residence exclusion work?
IRC Section 121 allows a single filer to exclude up to $250,000 of capital gain on the sale of a principal residence, and a married couple filing jointly to exclude up to $500,000. [3] Two tests must be satisfied during the five-year period ending on the date of sale: the ownership test (the seller owned the home for at least 24 months out of the five years) and the use test (the seller used the home as a principal residence for at least 24 months out of the five years). The two qualifying periods need not be the same 24-month window and need not be continuous.
A filer generally may not use the Section 121 exclusion more than once every two years. A partial exclusion is available when a sale before meeting the two-year tests is driven by a change in place of employment, a health-related reason, or unforeseen circumstances -- the exclusion is prorated by the fraction of the qualifying period completed. Depreciation taken on the property during periods of business or rental use is recaptured at a maximum 25 percent rate under Section 1250 and remains taxable even when the rest of the gain is excluded under Section 121. [3]
What special rates apply to collectibles and Section 1250 property?
Two categories of long-term capital gain face rates higher than the standard 0/15/20 percent schedule. First, gains from the sale of collectibles held more than one year -- including works of art, antiques, coins, stamps, metals such as gold and silver, and gems -- are taxed at a maximum 28 percent rate under IRC Section 1(h)(4). [1] For filers in the 10 or 12 percent ordinary-income brackets, the effective rate on collectibles gains is their actual bracket rate, not 28 percent; the 28 percent figure is a ceiling, not a floor.
How are capital losses deducted and carried forward?
Net capital losses offset net capital gains without limit in the same tax year. [1] When net capital losses exceed net capital gains, the excess offsets ordinary income up to $3,000 for single filers, married filing jointly, head of household, and qualifying surviving spouses -- and up to $1,500 for married filing separately. Net losses above that annual cap carry forward indefinitely to subsequent tax years, retaining their character as long-term or short-term. A filer who realizes a $20,000 net capital loss in 2025 may deduct $3,000 against 2025 ordinary income and carry $17,000 forward to 2026, applying the same rules in future years until the loss is exhausted.
The wash-sale rule under IRC Section 1091 limits loss harvesting. A sale at a loss followed by a purchase of the same or substantially identical security within 30 days before or after the sale date triggers disallowance of the loss; the disallowed amount is added to the basis of the replacement security and the original holding period carries over. The wash-sale rule applies across a filer's taxable accounts and extends to repurchases in a traditional or Roth IRA, where the disallowed loss is lost permanently rather than deferred.
For a plain-language overview of how the US federal tax system fits together, see the United States country overview. Filers dealing with stock options, restricted stock units, or carried interest may also benefit from reviewing US dividend and investment tax for the interaction of qualified-dividend rates with capital-gains brackets. Any filing that involves realized gains, loss carryforwards, or home-sale exclusions carries meaningful complexity; a credentialed tax professional familiar with your full financial picture is the appropriate resource before making disposition decisions.
US capital gains tax 2025: rates, brackets, exclusions, and reporting
US long-term capital gains on assets held more than one year are taxed at 0, 15, or 20 percent based on taxable income and filing status. Short-term gains on assets held one year or less are taxed at ordinary income rates of 10 to 37 percent.
A 3.8 percent Net Investment Income Tax applies above MAGI thresholds of $200,000 (single) and $250,000 (married filing jointly). The Section 121 principal-residence exclusion shelters up to $250,000 (single) or $500,000 (married filing jointly) of qualifying home-sale gain. All figures reflect IRS Rev. Proc. 2024-40 for tax year 2025.
What are the 2025 long-term capital gains tax rates for a single filer in the United States?
For tax year 2025, a single filer pays 0 percent on long-term capital gains within taxable income up to $48,350, 15 percent on gains that push taxable income from $48,351 through $533,400, and 20 percent on gains above $533,400. The thresholds are set annually by IRS Rev. Proc. 2024-40 and adjusted for inflation each year.
How are short-term capital gains taxed in the US?
Short-term capital gains on assets held one year or less are taxed as ordinary income at the filer's marginal income tax rate, which ranges from 10 to 37 percent across the seven federal brackets for 2025. Because short-term gains stack on top of other income, a filer in the top bracket can pay 37 percent federal on a short-term gain compared with 20 percent long-term.
What MAGI thresholds trigger the 3.8 percent Net Investment Income Tax?
The NIIT under IRC Section 1411 applies at 3.8 percent on the lesser of net investment income or MAGI above $200,000 for single filers and heads of household, $250,000 for married filing jointly and qualifying surviving spouses, and $125,000 for married filing separately. These thresholds are not indexed for inflation and have remained fixed since 2013.
Can a homeowner exclude gain from the sale of a primary residence?
Yes. IRC Section 121 excludes up to $250,000 of gain (single) or $500,000 (married filing jointly) on a qualifying principal-residence sale. The seller must have owned and used the home as a principal residence for at least two of the five years before the sale date and must not have used the exclusion within the prior two years.
How much of a capital loss can be deducted against ordinary income, and do unused losses carry forward?
Net capital losses that exceed net capital gains can offset ordinary income up to $3,000 per year (or $1,500 for married filing separately). Any remaining net loss carries forward indefinitely to future tax years, retaining its long-term or short-term character, and is applied under the same rules until fully used.
What does the IRS say crypto is for tax purposes?
The Internal Revenue Service established the foundational rule in Notice 2014-21: virtual currency is treated as property for US federal income tax purposes, not as foreign currency. That single classification carries through every downstream calculation. Gain or loss on the disposal of crypto is computed the same way as gain or loss on the sale of stock or other capital property. Holding-period rules determine long-term versus short-term character, and basis is tracked at the per-unit level in US dollars at the time of acquisition.
The Infrastructure Investment and Jobs Act of 2021 later codified a statutory definition of "digital asset" as "any digital representation of value recorded on a cryptographically secured distributed ledger," expanding the scope beyond the earlier convertible-virtual-currency framing and giving Treasury authority to write broker-reporting regulations [1].
What counts as a taxable disposal?
Because crypto is property, any change in ownership or deemed exchange triggers gain or loss recognition. The IRS FAQ guidance (updated through January 2025) confirms the following events are taxable disposals:
- Sale for fiat currency. Selling BTC, ETH, or any digital asset for US dollars (or foreign currency) is a taxable disposition. Gain or loss equals proceeds minus adjusted basis.
- Crypto-to-crypto exchange. Swapping Bitcoin for Ethereum is treated as a sale of Bitcoin at fair market value, with immediate gain or loss recognition. The acquired Ethereum takes a basis equal to its FMV at the time of exchange (IRS FAQ Q16-17) [2]. The Tax Cuts and Jobs Act of 2017 confined Section 1031 like-kind exchange treatment to real property, foreclosing that argument for crypto-to-crypto swaps after 2017.
- Payment for goods or services. Using crypto to pay a merchant or contractor is a disposal of a capital asset at its FMV on the date of payment. Gain or loss is the difference between that FMV and the adjusted basis of the crypto used.
- Receipt as compensation, mining, or staking. Crypto received as wages, self-employment income, mining proceeds, or staking rewards is ordinary income at FMV on the date received. Basis of the received crypto equals that same FMV.
Non-taxable events include purchasing crypto with fiat (no gain until disposal), transferring crypto between wallets with the same beneficial owner, and gifting crypto (the donor recognizes no gain; the recipient takes the donor's basis and holding period under IRC SS 1015).
How are short-term and long-term gains taxed?
Holding period for crypto follows IRC SS 1223: the period begins the day after acquisition and ends on the date of disposal. Crypto held one year or less produces short-term gain or loss taxed at ordinary marginal income tax rates. Crypto held more than one year produces long-term gain or loss taxed at the preferential rates set by IRC SS 1(h). The 2025 long-term capital gains brackets are [3]:
| Filing Status | 0% Rate | 15% Rate | 20% Rate |
|---|---|---|---|
| Single | Up to $48,350 | $48,351 - $533,400 | Above $533,400 |
| Married Filing Jointly | Up to $96,700 | $96,701 - $600,050 | Above $600,050 |
| Head of Household | Up to $64,750 | $64,751 - $566,700 | Above $566,700 |
Short-term gains are taxed at ordinary income rates of 10%, 12%, 22%, 24%, 32%, 35%, or 37% depending on taxable income. High-income filers are also subject to the 3.8% Net Investment Income Tax (NIIT) under IRC SS 1411, making the effective top rate 23.8% on long-term gains and 40.8% on short-term gains for filers subject to NIIT. The wash-sale rules of IRC SS 1091 do not currently apply to cryptocurrency because crypto is not a "security" under the statutory definition; a filer who sells at a loss and immediately repurchases the same digital asset may generally claim the loss [2].
How are staking rewards and mining income taxed?
Rev. Rul. 2023-14 settled the IRS position on staking: crypto received from proof-of-stake validation is gross income at fair market value in the taxable year the taxpayer gains dominion and control over the rewards. This applies whether the taxpayer stakes directly or through a custodial exchange. The FMV recognized at receipt becomes the basis for the staked tokens; a later disposal triggers a separate capital-gain calculation measured from that basis.
Mining rewards follow the same ordinary-income-at-receipt rule. If mining or staking is conducted regularly and continuously with a profit motive, the activity is likely a trade or business subject to self-employment tax; hobby-level activity avoids SE tax but deductions for associated expenses are no longer available as miscellaneous itemized deductions after the Tax Cuts and Jobs Act.
Hard-fork airdrops are ordinary income at FMV on the date the holder gains dominion and control over the new cryptocurrency, per Rev. Rul. 2019-24 [1].
What is Form 1099-DA and what does it cover?
Form 1099-DA (Digital Asset Proceeds From Broker Transactions) is the new information return from custodial digital-asset brokers - centralized exchanges, custodial wallet providers, and digital asset kiosks. Treasury finalized the broker-reporting framework in 2024. The phase-in calendar is:
- Tax year 2025 (forms issued by February 17, 2026): Brokers report gross proceeds for dispositions. Most 2025 forms show proceeds only; taxpayers must calculate their own basis.
- Tax year 2026: Brokers must also report cost basis for assets acquired through the broker on or after January 1, 2026. Revenue Procedure 2024-28 provides transition guidance for allocating unused basis as of January 1, 2025.
- Transition relief: Notices 2024-56 and 2025-33 confirm penalty relief for good-faith filing during 2025. Decentralized-finance protocols remain excluded from the broker definition pending further guidance (Notice 2024-57).
Each Form 1099-DA disposition flows to Form 8949 (Part I for short-term, Part II for long-term), with totals rolling to Schedule D and then to Form 1040. Every US filer must also answer the digital-asset question on the front page of Form 1040: "At any time during the tax year, did you (a) receive (as a reward, award or payment for property or services); or (b) sell, exchange, or otherwise dispose of a digital asset (or a financial interest in a digital asset)?" The question is required regardless of taxable activity; answering No when Yes is correct may be treated as a misrepresentation in subsequent compliance proceedings.
For the complete US capital-gains rate framework, see the United States country overview. A credentialed practitioner familiar with digital-asset reporting can reconcile 1099-DA discrepancies, establish specific-identification lot elections, and determine whether mining or staking activity rises to trade-or-business status - the credential-check page links the official lookups for checking a credential.
Cryptocurrency taxation in the United States: IRS rules, rates, and Form 1099-DA
The IRS classifies crypto as property (Notice 2014-21): every sale, crypto-to-crypto swap, or purchase with crypto is a taxable capital event. Short-term gains are taxed as ordinary income (10-37%); long-term gains at 0%, 15%, or 20% plus possible 3.8% NIIT. Staking rewards are ordinary income on receipt (Rev. Rul. 2023-14). Form 1099-DA broker reporting began for gross proceeds in 2025.
Does the IRS require tax to be paid when swapping one cryptocurrency for another?
Yes. The IRS treats each cryptocurrency as property under Notice 2014-21. Exchanging Bitcoin for Ethereum is a taxable disposal of the Bitcoin at its fair market value on the date of the swap (IRS FAQ Q16). Gain or loss is recognized immediately. The acquired Ethereum's basis equals its FMV at the time of exchange. Section 1031 like-kind treatment has not applied to crypto since 2018.
Are staking rewards taxable income when received, or only when sold?
Taxable when received. Rev. Rul. 2023-14 states that staking rewards are ordinary income at fair market value in the year the taxpayer gains dominion and control over the tokens - even if subject to a lock-up period. That FMV at receipt becomes the basis. A later sale or disposal of the staked tokens then triggers a separate capital-gain calculation.
What is Form 1099-DA and when did brokers start issuing it?
Form 1099-DA (Digital Asset Proceeds From Broker Transactions) is the new information return from custodial exchanges. Brokers began reporting gross proceeds for transactions on or after January 1, 2025; recipients receive those first forms by February 17, 2026. Cost-basis reporting becomes mandatory starting with tax year 2026 transactions. Most 2025 forms will show proceeds only - taxpayers must calculate their own basis.
More on United States
The rest of the United States reference is on the United States tax guide, in 3 parts: part 1, part 2, part 3.
- Do wash-sale rules currently apply to cryptocurrency losses?
- Must the Form 1040 digital-asset question be answered even when no crypto was sold?
- How are qualified dividends taxed in the US?
- What is the difference between qualified and ordinary dividends?
- What are the 2025 qualified dividend and long-term capital gains rate brackets?
- What is the Net Investment Income Tax?
- How are long-term capital gains taxed in the US?
- Dividend & Investment Tax in the United States (2026)
- What tax rate applies to qualified dividends in the US in 2025?
- What makes a dividend 'qualified' for the lower US tax rate?
- Who owes the 3.8% Net Investment Income Tax on dividends?
- How are ordinary dividends taxed if they are not qualified?
- Does the NIIT apply to dividends in retirement accounts?
- Why does the US tax citizens living abroad?
- How does the Substantial Presence Test determine US tax residency for non-citizens?
- What is the Foreign Earned Income Exclusion and how is it claimed?
- How does the Foreign Tax Credit offset double taxation?
- FBAR and FATCA: what foreign account reporting is required?
- What is the Section 877A exit tax for covered expatriates?
- US expat tax residency 2025: citizenship-based taxation, FEIE, FTC, FBAR, FATCA, and exit tax
- Do US citizens owe US income tax when living and working in another country?
- What is the Substantial Presence Test formula for US tax residency?
- What is the 2025 Foreign Earned Income Exclusion amount and how is it claimed?
- When must a US person file FBAR and Form 8938?
- What are the covered expatriate thresholds and how does the Section 877A exit tax work?
- What is the federal estate tax exemption for 2025 and 2026?
- How does portability of the deceased spouse's exemption work?
- How does the annual gift tax exclusion interact with the estate tax?
- What is step-up in basis at death?
- Do any states impose their own estate or inheritance tax?
- Federal Estate Tax in the United States: Exemptions, Gift Tax, and State Rules (2025-2026)
- What is the federal estate tax exemption for 2025?
- What did the One Big Beautiful Bill Act change for estate taxes in 2026?
- How does portability of a deceased spouse's estate tax exemption work?
- What is the 2025 annual gift tax exclusion and how does it relate to the estate tax?
- Which states impose an estate tax or inheritance tax in 2025?
- How Does Local Property Tax Work?
- What Are Current Property Tax Rates by State?
- How Do Homestead Exemptions and Assessment Caps Work?
- What Is the SALT Deduction Cap and How Did the OBBBA Change It?
- How Does the Property Tax Assessment Appeal Process Work?
- US Property Tax: How It Works, Rates by State, and the SALT Deduction
- Is there a federal property tax in the United States?
- Which states have the highest and lowest property tax rates?
- How did the One Big Beautiful Bill Act change the SALT deduction cap?
- What is California Proposition 13 and how does it limit property tax?
- How do I appeal my property tax assessment?
- How does self-employment (SE) tax work, and what is the 15.3% rate?
- What forms do self-employed filers use to report income and calculate SE tax?
- How do quarterly estimated taxes work, and when are payments due?
- What is the Qualified Business Income (QBI) deduction, and does it apply in 2025?
- What are the 1099-NEC and 1099-K reporting obligations for self-employed filers?
- Self-Employed Tax in the United States (2025): SE Tax 15.3%, Schedule C, Quarterly Estimates, and QBI
- What is the self-employment tax rate for 2025, and what is the Social Security wage base?
- When are 2025 quarterly estimated tax payments due for self-employed individuals?
- Is the Section 199A QBI deduction still available after 2025, and did the One Big Beautiful Bill Act change it?
- What is the 1099-K threshold for self-employed filers receiving payments via apps like PayPal or Venmo in 2025?
- Can a self-employed filer deduct home office expenses, and what are the two available methods?
- What federal tax forms do different business structures file?
- What is self-employment tax and how is it calculated?
- When and how do small businesses pay estimated taxes?
- How does the Section 199A qualified business income deduction work?
- Do I need an Employer Identification Number?
- US Small Business Tax 2025: Entity Types, SE Tax, Estimated Payments, and the QBI Deduction
- What is the 2025 Social Security wage base for self-employment tax?
- Is the Section 199A QBI deduction still available in 2025 and 2026?
- What is the federal corporate income tax rate for a C-corporation in 2025?
- When are quarterly estimated tax payments due for 2025?
- Does a sole proprietor or single-member LLC need an EIN?
- What do US income tax treaties actually reduce?
- What is the saving clause, and why does it matter for US citizens abroad?
- How does a nonresident alien claim treaty benefits? (Form W-8BEN and Form 8833)
- How does the residency tie-breaker resolve dual-resident status?
- What is the Foreign Tax Credit, and how does it relate to treaty relief?
- US Income Tax Treaties: Reduced Withholding, the Saving Clause, and How to Claim Relief
- How many countries does the United States have income tax treaties with?
- What is the saving clause in a US tax treaty?
- When is Form 8833 required to claim a treaty position?
- How does the Foreign Tax Credit differ from treaty-based relief?
- Are Social Security totalization agreements the same as income tax treaties?
- Does the United States have a federal VAT or national sales tax?
- Which states impose a sales tax, and what are the NOMAD states?
- How does economic nexus work after South Dakota v. Wayfair?
- What are marketplace facilitator laws?
- Resale certificates, exemption certificates, and use tax
- US sales tax explained: no federal VAT, state-by-state rates, economic nexus, and marketplace facilitator rules
- Does the United States have a federal VAT or national sales tax?
- Which five states have no sales tax?
- What did South Dakota v. Wayfair change for online sellers?
- Do marketplace sellers on Amazon or Etsy need to collect sales tax themselves?
- What is use tax and who owes it?
Frequently asked
Who is the tax authority in the United States?
The Internal Revenue Service (IRS) administers federal tax. It operates as a bureau of the US Treasury Department. State-level taxes are administered by separate state Departments of Revenue in each of the 41 income-tax states plus DC.
What is the US tax year and the filing deadline?
The federal tax year for individuals is the calendar year. The standard filing deadline is 15 April. A six-month automatic extension to file (not to pay) is available via Form 4868. Estimated tax is due in four quarterly installments — 15 April, 15 June, 15 September, and 15 January of the next year.
How is US tax residency determined?
US citizens are taxed on worldwide income regardless of where they live. Non-citizens are resident aliens if they meet the Substantial Presence Test under IRC §7701(b): 31 days in the current year plus 183 days across a three-year weighted formula. Green-card holders are residents from the day they obtain LPR status.
What are the federal personal income tax rates?
Seven brackets for tax year 2025: 10%, 12%, 22%, 24%, 32%, 35%, and 37%. The 37% top rate applies above roughly USD 626,350 single / USD 751,600 MFJ. The standard deduction for 2025 is approximately USD 15,000 single / USD 30,000 MFJ.
How does federal corporate tax work?
The federal corporate rate under IRC §11 is a flat 21% on taxable income. The Inflation Reduction Act added a 15% Corporate Alternative Minimum Tax for corporations with three-year average financial-statement income above USD 1 billion. State corporate tax stacks on top.
How does sales tax work in the United States?
There is no federal VAT or general sales tax. Sales tax is set state by state: 45 states plus DC impose one, with roughly 13,000 local jurisdictions adding city/county/special-district rates on top. Combined rates range from 0% in the 5 no-sales states to over 10% in some localities.
From TaxProsRated · our own product
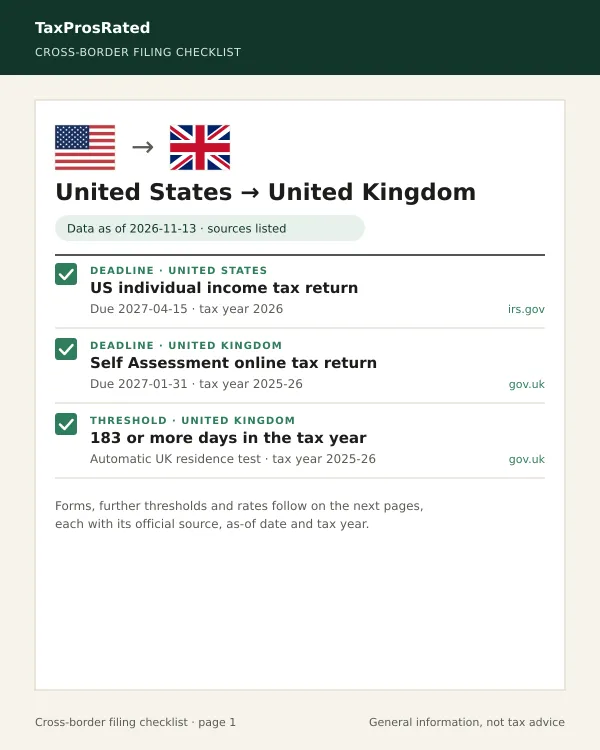
Cross-border filing checklist
- A PDF and a web copy of the checklist for the country pair you choose
- Filing deadlines for both countries, each with the official source URL and as-of date
- The forms named by each tax authority, with a link to the authority's own page
$29 one-time · One payment, no renewal. Tax, if any, is shown at checkout.
More countries in this region · All jurisdictions · United States filing deadlines · United States in the tax rates index · United States vs New Zealand · United States vs United Kingdom · United States vs Canada · United States vs Portugal · United States vs Spain · United States vs Mexico · United States vs United Arab Emirates · Cross-border filing checklist
United States tax guides
In-depth guides and explainers relevant to United States.
- United StatesGift Tax Basics: When Form 709 Is RequiredThe donor pays, and rarely owes. How the annual and lifetime exclusions interact, and why Form 709 matters most when no tax is due.
- United StatesTax Identity Theft and the IRS IP PIN ExplainedHow a stolen Social Security number becomes a fraudulent refund claim, what an IP PIN does to stop it, and who can now opt in.
- United StatesWhat to Bring to a Tax Preparer AppointmentThe records a preparer needs at a first appointment, the ones taxpayers most often forget, and the life events worth raising unprompted.
- United StatesThe Home Office Deduction, ExplainedWho qualifies for the home office deduction, the simplified vs regular method, and the exclusive-use test for self-employed filers.
- United StatesTax Filing Status, ExplainedThe five federal filing statuses and how each one affects your standard deduction, tax brackets, and credits.
- United StatesHow to Verify a Tax Preparer's CredentialsConfirm a paid preparer's IRS PTIN, search the IRS directory, and verify a CPA, enrolled agent, or attorney before you hire them.
Change log
- Country summary updated
- Rate source updated: capital-gains Source
- Rate source updated: corporate-income Source
- Rate source updated: personal-income-lowest Source
- Rate source updated: personal-income Source
- Rate source updated: inheritance
- Rate source updated: vat
- Rate updated: capital-gains Up to from 20% to 20 Source
- Rate updated: corporate-income from 21% to 21 Source
- Rate added: personal-income-lowest 10 Source
- Rate updated: personal-income from 37% to 37 Source
- Country summary updated
- Reviewed against Internal Revenue Service (IRS)
Sources
The figures, dates, and rules on this page are sourced from the documents listed below. Where two sources disagree, both are listed.
Important disclaimer
Informational only — not tax advice. This page summarises publicly available information about tax in United States as of November 2026. Tax laws change, individual circumstances vary, and the application of any rule depends on your specific facts.
TaxProsRated does not provide tax, legal, accounting, or financial advice. Before acting on anything you read here, consult a qualified tax professional licensed in your jurisdiction (in the US: CPA, Enrolled Agent, or attorney; in the UK: CIOT- or ATT-qualified adviser; in Australia: TPB-registered tax agent; elsewhere: a locally-licensed equivalent). TaxProsRated, its operators, and its contributors disclaim all liability for action taken in reliance on this page.